The IRS is taking your paycheck. Let's stop it.
Levies and garnishments are reversible — but the window is short. We file the release request, exercise your Collection Due Process rights, and move you out of acute danger.
An active levy doesn't pause for the holidays. It runs until the balance is satisfied or the levy is released. Every paycheck you wait is money the IRS keeps. The escalation from notice → lien → levy → seizure is a calendar, and you're somewhere on it.
How we fix it.
POA + transcript pull
Form 2848 filed; we get the IRS to recognize representation. Transcripts pulled to confirm exactly what's active and what the balance is.
Release request
Levy release filed with the assigned Revenue Officer or the ACS. With a hardship case, releases come within 5 – 10 business days.
CDP hearing
Where you're inside the 30-day Collection Due Process window, we file Form 12153 and freeze the levy while we negotiate.
Long-term plan
Installment agreement, CNC status, or OIC — chosen based on what holds the release in place permanently.
Why us for levies, liens & garnishment.
IRS Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make. Currently in law school.
Collection Due Process rights, used in time.
You have 30 days from a Final Notice of Intent to Levy (LT11/Letter 1058) to request a CDP hearing. Inside that window, collection freezes. Outside it, your options compress fast. We file CDPs.
Levy release vs. lien withdrawal — not the same thing.
A levy is active seizure (paycheck, bank). A lien is a public claim on assets. Releasing one does not release the other. Both have separate procedures, and both matter for your credit and your closing on a house.
Currently Not Collectible (CNC) — the underused option.
When current income barely covers allowable living expenses, CNC status pauses collection entirely. We file Form 433-F, document the hardship, and keep you out of collection while you rebuild.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or get your price in a minute.
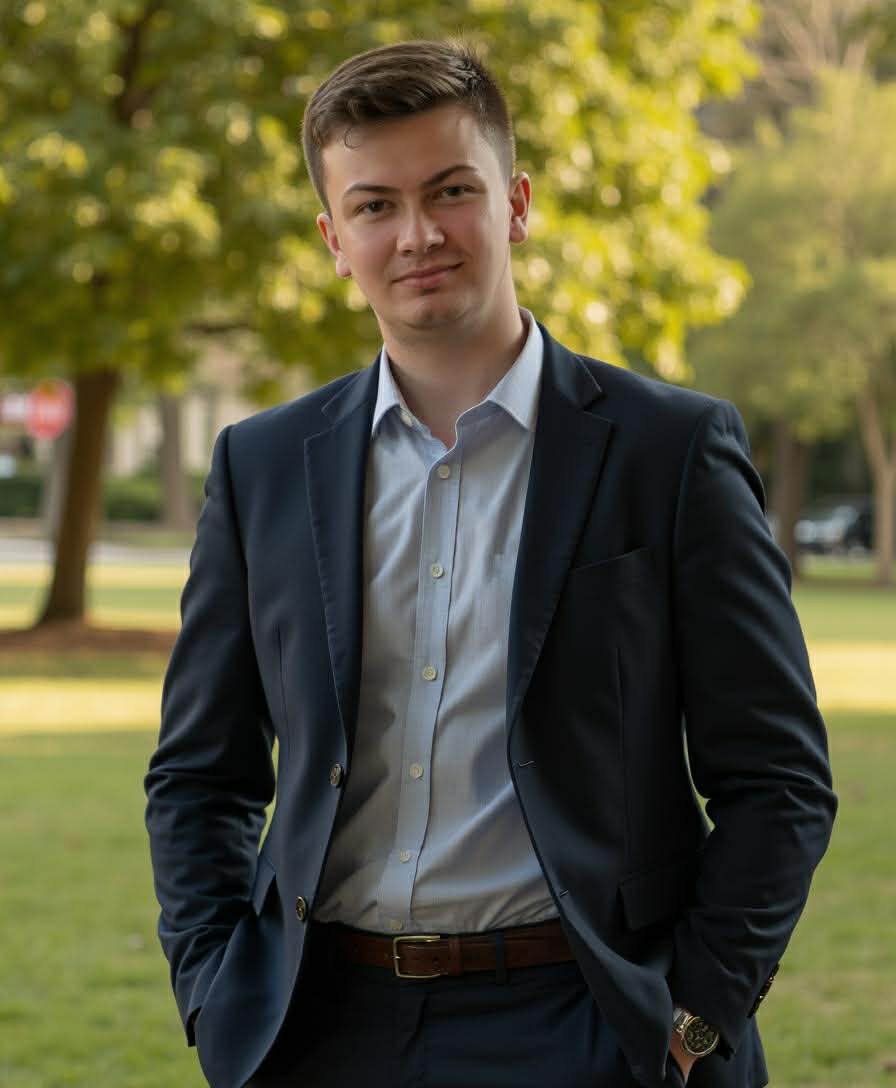
One practitioner. Every file, personally led.
Cody is an IRS Enrolled Agent with an MBA — a solo practitioner with a small support team, working out of Lakeland, Florida. He is also currently in law school.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful — and so when the IRS calls, the person who picks up is the person who filed your return.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
How fast can you get my paycheck back?
Once we have POA filed and a hardship case documented, levy releases typically issue within 5 – 10 business days. Faster with an assigned Revenue Officer; sometimes slower with ACS.
What if I missed the CDP window?
You can request an Equivalent Hearing (within 1 year) — similar process, but you lose the right to take it to Tax Court. We still file and negotiate; the leverage is weaker but real.
Can the IRS take my Social Security?
Yes, up to 15% under the Federal Payment Levy Program. Same release procedures apply.
My bank account was frozen — what now?
A bank levy is one-time but freezes the account for 21 days before remittance. We file the release inside that window; most frozen funds return.
Will the lien come off my credit report?
Federal tax liens haven't appeared on consumer credit reports since 2018. They're still public record and still affect lending and home sale. We file the withdrawal or release once the underlying liability is resolved.
Can I just ignore it and let it ride?
No. Levies don't expire on their own; they run until the balance is paid or the levy is released by the IRS. Every payday you wait costs you the levy amount.
Related
- IRS representationEvery representation fee published, handled by an Enrolled Agent.
- IRS payment plans and collectionsPayment plans, hardship status and levy releases, with the option you qualify for.
- Offer in compromiseSettling for less, only when the numbers really support it.
- IRS appealsAppeals, CDP hearings, innocent spouse relief and audit reconsideration.
Call now. This one is a calendar problem.
We file the POA the same day you call. Most clients see release inside two weeks.