Built for Florida green.
Equipment depreciation done by item. Crew payroll vs. 1099 classified correctly. Quarterly cash flow that respects the rainy-season dip and the spring rush. An accountant who actually understands the work.
Misclassified crew (1099 when they should be W-2) is the single most-audited issue in this space, and in Florida specifically. Equipment expensed when it should be capitalized inflates this year and starves next. Seasonal cash-flow without a tax-reserve discipline is the surprise April letter most owners get every year.
How we fix it.
Worker classification audit
Each crew member, by IRS factors. W-2 employee or 1099 contractor — and the documentation that holds up to the FL Department of Revenue.
Equipment + vehicle
Mowers, blowers, trailers, trucks. §179 elections by item, vehicle depreciation by method, fleet maintenance posted to GL.
Quarterly + seasonal planning
Tax reserve set on every deposit. Quarterly estimateds sized to the season. No April surprises — the dollars are already separated.
Annual return
Sch C or S-Corp depending on net profit. Sales tax on retail goods where applicable. Workers comp coordinated with payroll.
Why us for landscapers & lawn care.
Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make.
Worker misclassification — the audit waiting to happen.
FL DOR aggressively audits landscape companies for misclassified workers. Direction of work, supplied tools, set hours, exclusivity — all matter. We document classifications that hold up.
Equipment — §179 on the right items, in the right year.
A $14K zero-turn is §179. A $700 trimmer is a supply. We split them, and we time the §179 elections against your profit so the deduction lands when it counts.
Seasonal cash flow — tax reserves, every deposit.
Spring and early-fall revenue dwarfs winter. Most owners spend the spring cash and then can't pay April taxes. We set a tax reserve discipline (typically 22-28% of deposits) so the bill is already funded.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or start your intake.
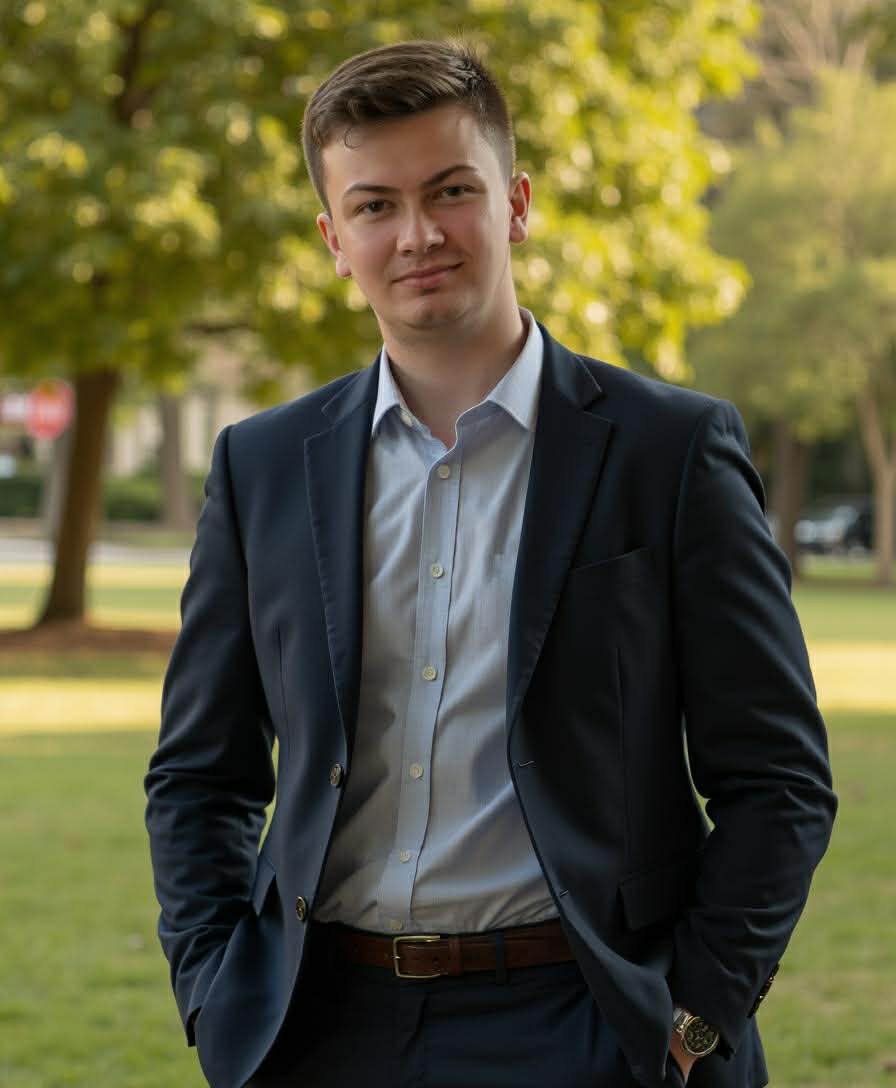
One practitioner. Every file, personally led.
Cody is an Enrolled Agent with an MBA, a solo practitioner with a small support team, working out of Lakeland, Florida.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful. The person who filed your return is the person who handles the IRS.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
Are my crew employees or contractors?
Depends on the facts. If you set their hours, supply the equipment, and direct the work — they're employees. If they bring their own crews and equipment and work for multiple companies — they're contractors. We document either way.
Should I be an S-Corp?
Once net profit reliably clears $60K – $80K, almost always. Below that, the payroll filings eat the savings.
Can I deduct my truck?
Yes — mileage or actual expenses, plus §179 / bonus depreciation on purchase year. A dedicated work truck typically optimizes under actual expenses with depreciation.
Do I owe sales tax?
Service revenue is generally not taxable in Florida; retail sales (sod, mulch sold separately) are. We file the right monthly sales-tax return.
What about fuel?
Off-road fuel for equipment may qualify for a federal excise-tax credit on Form 4136. Diesel especially. We file it.
Workers comp?
Florida requires it once you cross 4 employees in landscape (1 in construction). We coordinate the payroll and the carrier filing.
Related
- Business tax preparationS corp, partnership, C corp and Schedule C returns, with the owner's return included.
- S corp tax servicesWhether the election pays, Form 2553, a salary you can defend, and the 1120-S.
- Monthly bookkeepingMonthly close and reconciliations from the firm that files your return.
- Contractors and tradesJob costing, per diem, equipment and subcontractor 1099s.
The grass keeps growing. The books should too.
Send last year's return and a current crew list. We'll confirm the package and the add-ons on the first call.
Tell us about your business.
A few questions, then pick a time for a free 15-minute call with Cody. Nothing starts until you sign an engagement letter.
Prefer to talk? Call (863) 370-8115 or Book a 15-minute call.
Form not loading? Open it in a new tab, or call (863) 370-8115.