Miss three years in a row
and the exemption ends itself.
Form 990, 990-EZ, 990-PF, 990-T and 1120-H prepared by an Enrolled Agent. A fixed fee, quoted upfront to the board before any work starts. Never hourly.
Automatic revocation under §6033(j) involves no hearing, no examination and no IRS decision you can argue with. Three consecutive years without a filing of any kind and the exemption ends on the due date of the third one. The organization then appears on the IRS Auto-Revocation List, which grant officers and major donors check before they write. Contributions stop being deductible. The organization is treated as a taxable corporation for every year after that, and getting the exemption back means a fresh application, a fresh user fee and months of waiting — with a daily late-filing penalty running the whole time.
How we fix it.
Which return you actually file
We check gross receipts and total assets against the thresholds and tell you whether this is a 990-N, a 990-EZ, a full 990, a 990-PF or an 1120-H. Booster clubs, youth leagues, lodges, chambers, animal rescues, foundations, churches, condo and homeowners associations — each lands somewhere different, and several of them land on no return at all. Everything moves through a secure portal, so no board member has to make an office visit or hand over a paper file.
Fee quoted in writing
A fixed fee, given to the board before you engage, based on the form, the schedules your facts actually require, and whether the books are closed. Never an hourly meter, and never a figure that moves after the work starts. It goes in the budget as one line.
Return prepared
Revenue and functional expenses tied to your books, the Schedule A public support test run across the full five-year window, Schedule B donors handled under the disclosure rules, unrelated business income separated by activity, and the governance questions in Part VI answered rather than left blank.
Filed and public
Filed electronically, which the IRS requires for the entire 990 series. You get the exact copy that becomes public, plus a short written memo on what to fix in the books before next year so the same questions do not come back.
Why us for nonprofits, HOAs and foundations.
Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make.
Gross receipts pick the form, and the thresholds are bright lines.
Normally $50,000 or less in gross receipts and you file the 990-N e-Postcard. Under $200,000 in gross receipts and under $500,000 in total assets and you may use the 990-EZ. At or above either figure it is the full 990. A private foundation files a 990-PF at any size, including a family foundation whose only activity is a brokerage account — and that return carries the excise tax on net investment income and the annual distribution requirement with it.
An HOA is usually not a tax-exempt organization at all.
Most Florida associations are ordinary taxable corporations that elect §528 treatment by filing Form 1120-H: 60% of income from members, 90% of spending on the property, a flat 30% rate on everything else, and a $100 specific deduction. The election is made by filing the form, and it is made again every year. An 1120-H is also due April 15, not May 15 — which is how associations end up late on a deadline they were sure they knew.
Unrelated business income is where the exemption gets tested.
Gross unrelated business income of $1,000 or more means a Form 990-T and the unrelated business income tax (UBIT) that comes with it. Booster club advertising sold as sponsorship, a gift shop, debt-financed rental property, a parking lot rented to the public. Since §512(a)(6), each unrelated trade or business is computed on its own, so a loss in one cannot shelter income in another. We separate the activities before the IRS does it for you.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or start your intake.
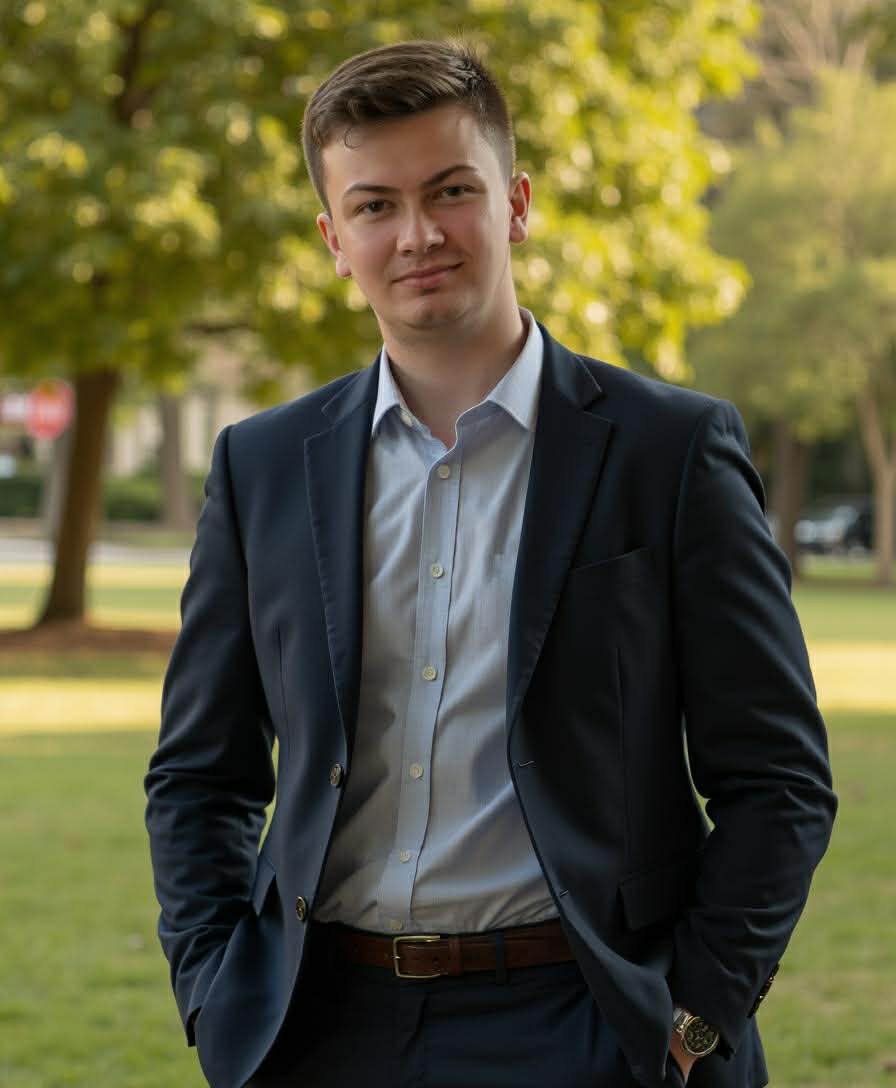
One practitioner. Every file, personally led.
Cody is an Enrolled Agent with an MBA, a solo practitioner with a small support team, working out of Lakeland, Florida.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful. The person who filed your return is the person who handles the IRS.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
Which 990 do we file?
Gross receipts normally $50,000 or less: the 990-N e-Postcard. Gross receipts under $200,000 and total assets under $500,000: the 990-EZ. At or above either one: the full 990. A private foundation files a 990-PF regardless of size. The e-Postcard counts as a filing, which matters — skipping it for three years revokes the exemption exactly the same way skipping a full 990 does.
When is it due?
The fifteenth day of the fifth month after your year end. For a calendar-year organization that is May 15 — and in 2027, May 15 falls on a Saturday, so the deadline is Monday, May 17, 2027. Form 8868 gets you an automatic six months to November 15. An association filing an 1120-H is on the corporate calendar instead: April 15, extended six months to October 15 on Form 7004.
We have not filed in three years. Is the exemption gone?
If three consecutive years passed with no filing of any kind, yes — automatically, on the due date of the third year, under §6033(j). It is not a judgment call and the revocation itself is not appealable. Reinstatement is a new exemption application under Rev. Proc. 2014-11, which includes a streamlined retroactive path for organizations small enough to file the 990-EZ or 990-N if you apply within fifteen months. We prepare the back returns and the application together. We will not tell you how the IRS is going to rule on it.
We are a church. Do we file a 990?
Churches, their integrated auxiliaries and conventions of churches are not required to file an annual 990. That is in the statute, not a policy that changes. You do file a 990-T if the church has $1,000 or more of gross unrelated business income, and you still have to run ministerial payroll correctly — a housing allowance is excluded from income tax but not from self-employment tax. If a 990 is not required, we say so on the first call instead of selling you one.
Does our HOA file a 990 or an 1120-H?
Almost certainly an 1120-H, and almost certainly your association is not a 501(c)(3). A homeowners or condo association that meets the §528 tests elects Form 1120-H by filing it. Member assessments are exempt function income and are not taxed; the flat 30% rate applies only to the rest — interest earned on reserves, laundry income, rent from non-members, cell tower leases. Some associations pay less on a regular Form 1120. We run both before we file either.
What else does Florida want from us?
Three things, and only one of them is a tax return. A Florida nonprofit corporation files an annual report with the Division of Corporations by May 1 — not a tax filing, and the one most often missed. If you solicit contributions in Florida you register with FDACS under Chapter 496 and renew it every year. And if the organization has unrelated business income, it generally files a Florida F-1120 alongside the 990-T. We flag all three at intake.
Related
- Trust and estate tax returnsForm 1041, 706 and 709, with a fixed fee quoted before work starts.
- Monthly bookkeepingMonthly close and reconciliations from the firm that files your return.
- PayrollPayroll run, taxes deposited and filed, W-2s and Florida reemployment tax.
- Business tax preparationS corp, partnership, C corp and Schedule C returns, with the owner's return included.
Get the 990 filed. Then get it off the board agenda.
Send last year's return, your year-end financials and your determination letter. We will tell you which form you actually owe, what it costs, and whether you owe one at all — in writing, before you engage.
Tell us about your organization.
A few questions, then pick a time for a free 15-minute call with Cody. Nothing starts until you sign an engagement letter.
Prefer to talk? Call (863) 370-8115 or Book a 15-minute call.
Form not loading? Open it in a new tab, or call (863) 370-8115.