Rental properties, done by an accountant who gets it.
Schedule E by property. Depreciation done right. Passive-loss netting, REPS qualification, and cost-segregation referrals — coordinated, not improvised.
Depreciation left on the table never comes back. Passive losses you can't use this year may carry forward usefully — or be permanently grouped wrong. The STR loophole works only if you actually qualify; assuming it works without confirming is a fast audit adjustment.
How we fix it.
Property-by-property intake
Purchase docs, financing, current rent roll, and last year's Sch E for each door. We rebuild the depreciation schedule if needed.
Schedule E build
One Sch E per property, separate columns. Depreciation, repairs vs. improvements, mortgage interest, RE taxes, insurance, management — all coded.
Passive activity review
§469 grouping election (or revocation). Carryforward losses tracked. STR loophole confirmed where material-participation evidence exists.
REPS / cost-seg referrals
Where REPS qualification is on the table, we run the hours analysis. Where cost segregation is worth it, we coordinate with the engineering firm.
Why us for real-estate investors.
IRS Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make. Currently in law school.
Schedule E per property — not aggregated.
The IRS expects each property on its own column. So do future buyers when they do diligence on your portfolio. We separate them properly.
Depreciation, passive losses, and the §469 grouping election.
Whether your rentals are grouped, whether you've made the real-estate-trade-or-business election, and whether you qualify as a real-estate professional all change what your losses are worth. We map them.
Cost segregation — referrals, not improvisation.
Cost-seg studies are engineering work, not accounting. We coordinate with engineering firms we trust, and we model whether the depreciation acceleration is worth the study cost before you commission it.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or get your price in a minute.
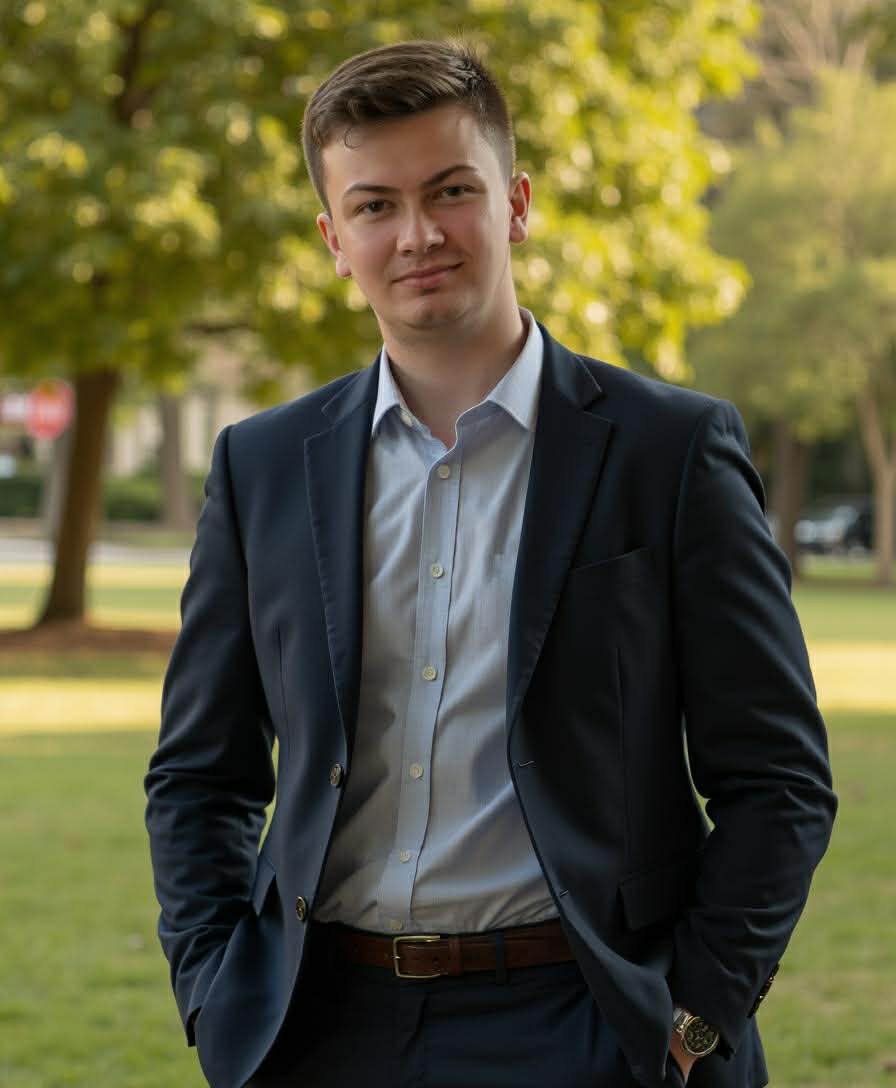
One practitioner. Every file, personally led.
Cody is an IRS Enrolled Agent with an MBA — a solo practitioner with a small support team, working out of Lakeland, Florida. He is also currently in law school.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful — and so when the IRS calls, the person who picks up is the person who filed your return.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
Do I qualify as a real-estate professional?
750+ hours/yr in real-property trades or businesses, AND more time in real estate than in any other job. The hours log is the whole game. We tell you, on the numbers, whether you actually qualify.
Should I do a cost-seg study?
Often yes for properties over $500K basis, especially in the first year of ownership. The bonus-depreciation step-down is changing the math; we model your property before you commission a study.
What's the STR loophole?
Average guest stay under 7 days + material participation = STR rental income/loss treated as active, not passive. Losses then offset W-2 — without REPS. Powerful, narrow, audit-target.
Can I deduct my time managing the rental?
No — your own labor isn't a deduction. But it can be the basis for REPS qualification, which changes loss treatment.
I sold a property — what about 1031?
If you used a qualified intermediary and identified replacement property within 45 days / closed within 180, we report the deferral on Form 8824. If you didn't, we plan the gain.
Multi-state portfolio — do you file all the states?
Yes. Resident state + non-resident return in each state with rental property. Credit for taxes paid set up so you don't double-pay.
Related
- Business tax preparationS corp, partnership, C corp and Schedule C returns, with the owner's return included.
- S corp tax servicesWhether the election pays, Form 2553, a salary you can defend, and the 1120-S.
- Monthly bookkeepingMonthly close and reconciliations from the firm that files your return.
- Real estate taxRentals, short-term rentals, flips and agent commissions.
Run the portfolio through someone who actually reads §469.
Send last year's return and a rent roll. We'll tell you what's working and what isn't.