Equipment, memberships, and trainers — on the books.
Equipment §179'd. Membership revenue recognized over the term. Trainers classified properly (W-2 or 1099). S-Corp election timed to your real numbers. Built for studio owners and independent trainers alike.
Membership revenue paid annually but recognized monthly distorts the P&L when booked cash-basis. Equipment depreciation done as supplies wastes §179 elections. Independent-contractor trainers misclassified expose you to back-payroll and workers-comp liability. Personal-trainer Sch C clients overpay SE tax on every renewal client.
How we fix it.
Entity check
S-Corp election once net profit clears the threshold. Sole-prop trainers, single-studio LLCs, and multi-location operators each have their own optimal structure.
Membership revenue
Annual memberships deferred and recognized monthly. ClassPass, Mindbody, Wodify, Trainerize integrated to the GL.
Equipment + build-out
Racks, plates, treadmills, mirrors, tenant improvements. §179, bonus depreciation, and cost-seg on owned studios.
Trainer classification
W-2 or 1099, by IRS factors. Documented arrangements that hold up to FL DOR scrutiny.
Why us for trainers & gym owners.
IRS Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make. Currently in law school.
Membership revenue — earned, not received.
A $1,500 annual membership sold in January is revenue earned across the whole year, not January revenue. Booked all at once, it inflates Q1 and overstates tax. Most studio software handles this if you set it up; we do.
Trainer classification — W-2 or 1099 by the facts.
Trainers who set their own rates, schedule their own clients, and work for multiple studios may be 1099. Trainers on your schedule, your pricing, your floor are employees. Misclassification is the FL audit-trigger here.
Equipment §179 in heavy-buildout years.
Opening or expanding a studio means six figures of racks, plates, machines, mirrors, sound systems. The §179 + bonus stack on equipment and tenant improvements often takes the first year to a $0 federal tax bill.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or get your price in a minute.
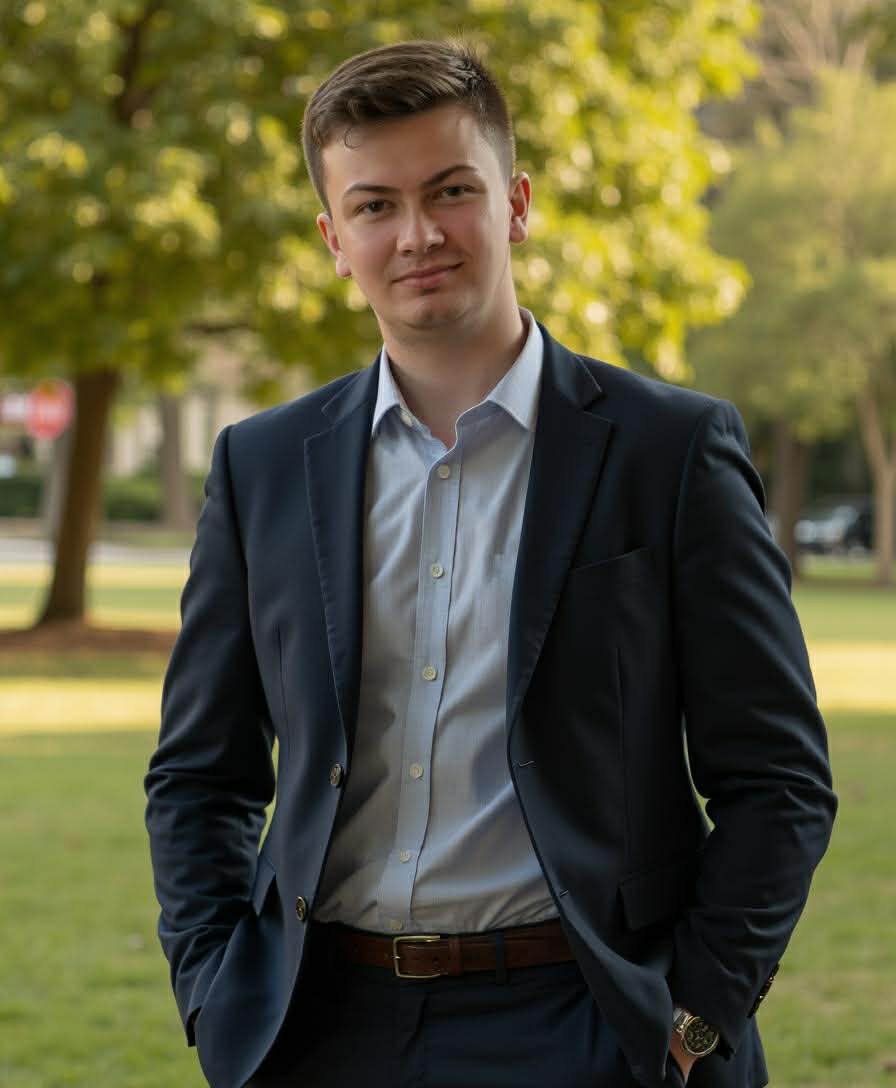
One practitioner. Every file, personally led.
Cody is an IRS Enrolled Agent with an MBA — a solo practitioner with a small support team, working out of Lakeland, Florida. He is also currently in law school.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful — and so when the IRS calls, the person who picks up is the person who filed your return.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
Should I be an S-Corp?
Once net profit clears $60K – $80K, almost always. Below that, payroll overhead eats the savings.
Trainers — W-2 or 1099?
Depends on the facts. If they're on your schedule, in your studio, using your equipment, taking your clients — they're employees. If they bring their own book and rent floor time — they may be contractors. We document either way.
Can I deduct my home gym?
If you train clients in it, partially yes — under §280A like a home office. If it's personal-use, no.
Membership cancellations and refunds?
Reversed against revenue as they occur. Tracked separately for reporting and KPI purposes.
Multi-location franchise (e.g. Orangetheory)?
Common. Each location often as a separate entity under a holding company. We structure and consolidate.
Cost-seg on a studio buildout?
Often worth it for buildouts over $400K. The bonus-depreciation step-down is changing the math; we model your buildout.
Related
Build the body. Build the books.
Send last year's return and a current membership report. We'll confirm the package and the add-ons on the first call.