Settle your tax debt for less than you owe — when you actually qualify.
Most OIC ads are noise. We run the IRS's reasonable-collection-potential math first; if you qualify, we file it. If you don't, we say so — and we lay out the alternative.
Frivolous OICs get rejected and cost you the application fee, the offered amount, and twelve months of standstill. Filing without the eligibility math is the most common reason these fail — and the most expensive lesson on the menu.
How we fix it.
RCP analysis
We compute your Reasonable Collection Potential — the IRS's actual measure of what you can pay. If RCP exceeds the balance, OIC isn't your tool, and we'll tell you on the call.
Form 656 packet
Doubt as to Collectibility (DATC), Doubt as to Liability (DATL), or Effective Tax Administration. We pick the basis that fits your facts and assemble the financial disclosure.
Negotiation
The IRS counters most offers. We handle the back-and-forth, supplemental documentation, and any escalation to Appeals where the agent gets it wrong.
Post-acceptance compliance
You must stay current — file and pay on time — for five years after acceptance, or the OIC defaults. We keep you compliant.
Why us for Offer in Compromise.
IRS Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make. Currently in law school.
RCP math, not a sales pitch.
The IRS uses a formula: future income + net realizable equity in assets. If your RCP exceeds the balance, you don't qualify — and no amount of paperwork changes that. We compute it before we charge a flat fee.
DATL vs. DATC — pick the right basis.
Doubt as to Collectibility (you can't pay) and Doubt as to Liability (you don't owe) are different cases with different evidence. Filing the wrong basis is a fast rejection.
The most common rejection reasons.
Underreported income on Form 433-A, dissipated assets in the lookback window, non-current filings, equity in retirement accounts the IRS values higher than you do. We screen for all of them up front.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or get your price in a minute.
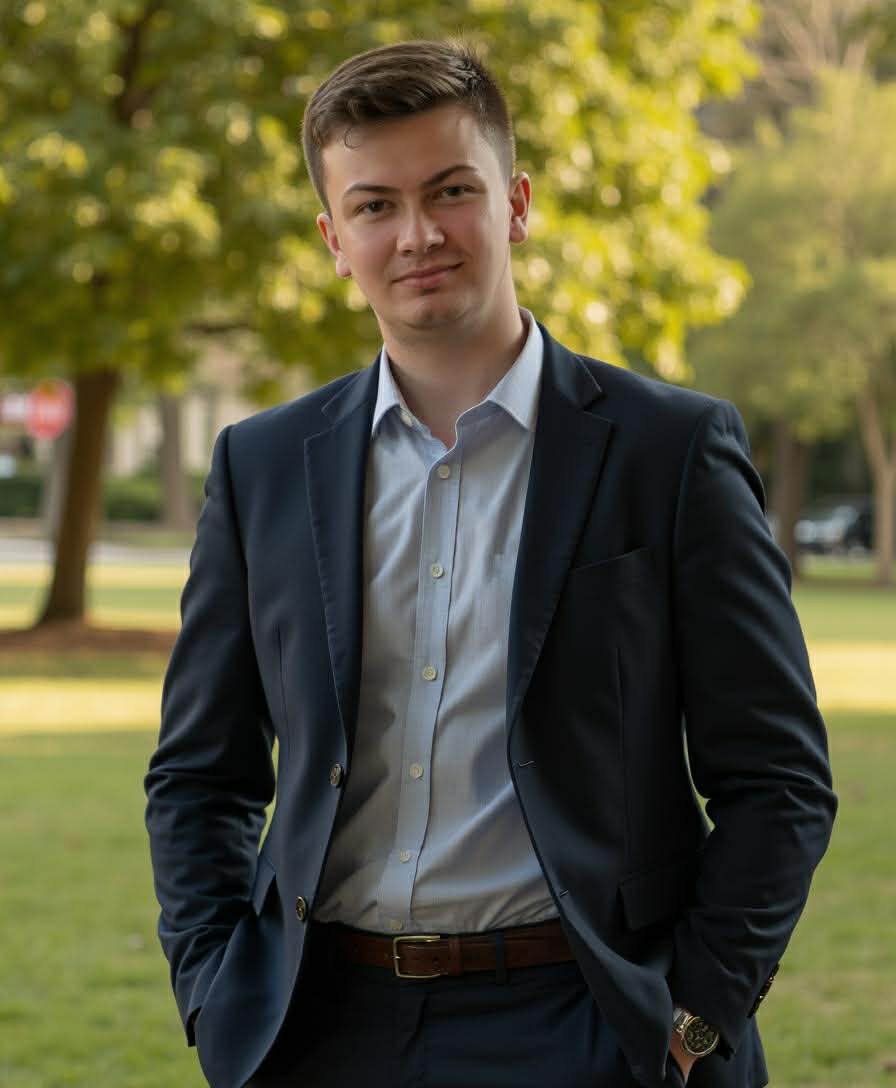
One practitioner. Every file, personally led.
Cody is an IRS Enrolled Agent with an MBA — a solo practitioner with a small support team, working out of Lakeland, Florida. He is also currently in law school.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful — and so when the IRS calls, the person who picks up is the person who filed your return.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
Do I qualify for an OIC?
You qualify if your Reasonable Collection Potential (future income + asset equity) is less than what you owe. We compute it first. About 30–40% of people who call think they qualify; about 12–15% actually do.
How long does it take?
9 to 14 months from filing to acceptance, typically. Collection activity pauses while the offer is being reviewed.
How much will the IRS accept?
Whatever your RCP works out to be — that's the floor. There's no magic discount; the formula is the formula. We negotiate at the edges (asset valuations, expense allowances) where there's room.
What if my offer is rejected?
You can appeal within 30 days; we file the protest. Many rejected offers are accepted on appeal when the underlying RCP is documented properly.
What happens if I miss a payment afterward?
The OIC defaults and the IRS reinstates the original balance plus interest from the original due date. The 5-year compliance window after acceptance is non-negotiable — we keep you on track.
Will an OIC hurt my credit?
The IRS doesn't report to credit bureaus. Existing federal tax liens may already be on your record; OIC acceptance triggers a lien-release request which we file.
Related
- IRS representationEvery representation fee published, handled by an Enrolled Agent.
- IRS payment plans and collectionsPayment plans, hardship status and levy releases, with the option you qualify for.
- Wage garnishment, liens and leviesStopping a garnishment or bank levy, starting the day you call.
- Unfiled tax returnsWe pull your IRS records and file the missing years, quoted at intake.
Find out if you qualify. First — before anything else.
The $600 eligibility review is the cheapest decision in tax controversy. We tell you the truth on the call.