The trust files its own return.
So does the estate.
Form 1041, Form 706 and Form 709 prepared by an Enrolled Agent. A fixed fee, quoted upfront in writing before any work starts. Never hourly, and never a number that moves after you engage.
A trust reaches the top 37% federal bracket in the low five figures of retained income, at a threshold the IRS indexes every year. A married couple does not get there until several hundred thousand. Distribute a few weeks late and the same dollar is taxed at the trust's rate instead of a beneficiary's. Beneficiaries cannot finish their own 1040 until your K-1 arrives, so a late 1041 makes four other people late. And an executor who distributes an estate before the government's claim is paid can be held personally liable for the balance under 31 U.S.C. §3713 — out of their own money, not the estate's.
How we fix it.
Intake and document list
Upload the trust instrument or the will, the letters testamentary, the EIN assignment letter, the date of death, and the prior year 1041 if one exists. Everything moves through a secure portal; no office visit. We send back a written list of what is still missing, so nobody has to guess.
Fee quoted in writing
We read the documents, count the beneficiaries, and give you the fee for this return before you engage. What moves it: the number of K-1s, whether the trust holds rental or operating property, whether a 706 is required, how many states the assets sit in, and whether prior years were left unfiled.
Return prepared
Income and principal split under the instrument and state law, distributable net income and the income distribution deduction computed from the statements the bank and the brokerage actually issued, and a Schedule K-1 produced for every beneficiary. That is the tax work. We do not produce the formal fiduciary accounting itself, and we do not audit, review or compile financial statements.
Filed, K-1s delivered
A calendar-year 1041 is due April 15 and extends five and a half months to September 30 on Form 7004. We file, deliver each beneficiary their K-1, and tell you plainly what the final year of the trust or the estate is going to look like.
Why us for trustees and executors.
Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make.
Revocable, irrevocable, and which one actually files.
A revocable living trust files nothing while the grantor is alive — it reports on the grantor's own Social Security number. The day the grantor dies it becomes irrevocable, needs its own EIN, and begins filing a 1041. Most of the calls we get are from a successor trustee who did not know that day had arrived, and is now nine months into a filing year nobody started.
The 65-day rule is the only do-over you get.
Under §663(b), an estate or a complex trust can elect to treat a distribution made in the first 65 days of the new year as if it were made in the prior year. For a calendar-year trust filing for 2026, the sixty-fifth day is March 6, 2027, which is a Saturday — and the rule runs on the distribution, not on the paperwork, so the money has to actually leave the account by Friday, March 5, 2027. It is the one lever that moves income out of the trust's compressed brackets and onto a beneficiary's return, and it expires quietly.
The 706 and the 709 are often filed when no tax is owed.
The federal exclusion is $15 million per person for deaths in 2026, indexed after that, and Florida has no estate tax and no inheritance tax — so most estates owe nothing. The reason to file a 706 anyway is portability: it is how a surviving spouse keeps the first spouse's unused exclusion, and Rev. Proc. 2022-32 allows that election up to five years after the death for estates not otherwise required to file. A 709 works the same way. Giving one person more than the annual exclusion ($19,000 for 2026), splitting gifts with a spouse, or funding a 529 with five years of exclusions at once all require the return. Almost none of them create a tax bill.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or start your intake.
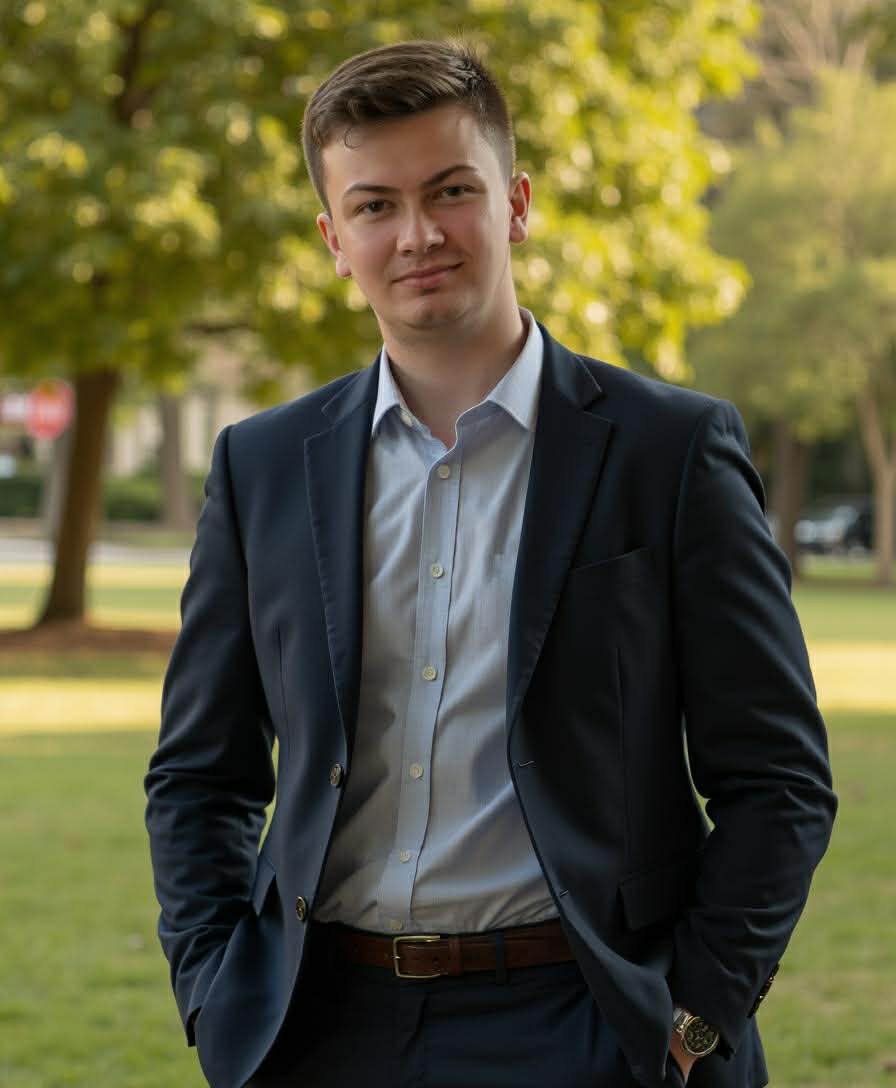
One practitioner. Every file, personally led.
Cody is an Enrolled Agent with an MBA, a solo practitioner with a small support team, working out of Lakeland, Florida.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful. The person who filed your return is the person who handles the IRS.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
Do we even have to file a 1041?
An estate files when it has $600 or more of gross income for the year. A trust files when it has any taxable income at all, or $600 or more of gross income, or a beneficiary who is a nonresident alien. A revocable living trust files nothing while the grantor is living. If none of those apply to you, we will tell you on the first call and you will not owe us anything for the answer.
When is everything due?
A calendar-year 1041 is due April 15 and extends to September 30 on Form 7004. An estate may instead elect a fiscal year ending up to eleven months after the date of death, which can buy a great deal of room; the return is then due the fifteenth day of the fourth month after that year end. A Form 706 is due nine months after the date of death and extends six months on Form 4768. A Form 709 is due April 15 of the year after the gift, and extending your own 1040 extends it with you.
Who pays the tax — the trust or the beneficiary?
Whoever received the income. A simple trust distributes all of its income every year, so the beneficiaries are taxed on it and the trust gets a deduction for it. A complex trust or an estate chooses, within the limits of the instrument and distributable net income. Because the trust's brackets compress so fast, the distribution decision is usually the largest number on the return, and the 65-day election is how it gets fixed after year end.
What do you need from a trustee?
The trust instrument and every amendment, the EIN assignment letter, the prior year 1041, the 1099s for every account the trust holds, closing statements for anything bought or sold, a list of every beneficiary with name, address and Social Security number, a dated record of the distributions made during the year, and any trustee fee records. If the trust holds a rental or an operating business, add that year's books.
What do you need from an executor?
The death certificate, the will, the letters testamentary or letters of administration the probate court issued, the estate EIN, the decedent's last filed 1040, date-of-death values for every account and every piece of property, medical and funeral expense records, and the list of beneficiaries under the will. Get those date-of-death values right the first time: the step-up in basis a beneficiary reports a later sale against is computed off them. If a refund is due on the final 1040 and you are neither the surviving spouse nor a court-appointed representative, add Form 1310. We will also ask whether Form 56 has been filed, and file it if it has not.
Are you a CPA firm? Do you give legal advice on the trust or the will?
No to both, and we would rather say it now than at the end. Ring Tax is an Enrolled Agent firm: enrolled to represent taxpayers before the IRS, with unlimited rights to represent clients before the IRS. We are not a CPA firm, so if a court, a bank or a beneficiary wants audited, reviewed or compiled financial statements, that is CPA work, we do not do it, and we will tell you so and point you to someone who does. We are not a law firm either. We read the instrument in order to apply it to the return, and we prepare and file the returns. We do not draft it, amend it, interpret ambiguous language in it, or advise you on your duties as a fiduciary. Those questions belong to the estate attorney, and we say so the moment one comes up — including when you do not have an attorney yet and need one.
Related
- Individual tax preparationYour household return, one state and investment sales, from $650 a year.
- New Florida residentsThe part-year return for the state you left and the records that prove you moved.
- Real estate taxRentals, short-term rentals, flips and agent commissions.
- CRNAs, NPs, locums and travel nursesW-2 or 1099, multi-state work and the entity question.
- Tax planningQuarterly estimates and a written plan before year end, while the moves still count.
Send us the instrument. You will have the fee before you have a bill.
Upload the trust or the will, the EIN letter and last year's return. We read it, quote the return in writing, and tell you what your actual deadline is — which is often further out than you think.
Tell us about the trust or estate.
A few questions, then pick a time for a free 15-minute call with Cody. Nothing starts until you sign an engagement letter.
Prefer to talk? Call (863) 370-8115 or Book a 15-minute call.
Form not loading? Open it in a new tab, or call (863) 370-8115.