The IRS sent you a CP2000.
Don't answer it alone.
Enrolled Agent representation. We respond to the IRS on your behalf, dispute incorrect adjustments, and protect you from further penalties.
Default judgment. Accrued penalties and interest. An expanded audit scope if the response is mishandled. Most CP2000s carry a 30-day clock — and the IRS does not extend it because you were busy.
How we fix it.
Secure intake
You send the notice, your last filed return and a signed Form 2848 (Power of Attorney) through your secure TaxDome portal.
Diagnosis
We pull your IRS transcripts directly and identify whether the proposed adjustment is correct, partially correct, or wrong.
Response filed
We draft and file the written response. The IRS now talks to us, not you. Most CP2000s close in one cycle.
Penalty review
Even on a justified balance, we petition for penalty abatement where the facts support it.
Why us for CP2000 & IRS notices.
Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make.
CP2000 vs. CP14 vs. LT11 — they're not the same letter.
A CP2000 is a proposed change. A CP14 is a balance due. An LT11 is an intent to levy. Each has a different deadline, a different defense, and a different cost of getting it wrong. We respond to all three.
Agreeing without review often costs more than fighting.
The IRS proposes adjustments based on missing 1099s, broker basis errors, or duplicate W-2 reporting — many of which are wrong. We reconcile against your actual records before you sign anything.
The statute of limitations is a weapon, not a footnote.
Some notices reach back to years that are already time-barred from assessment. We check the statute on every file. If the IRS missed its window, we say so.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or start your intake.
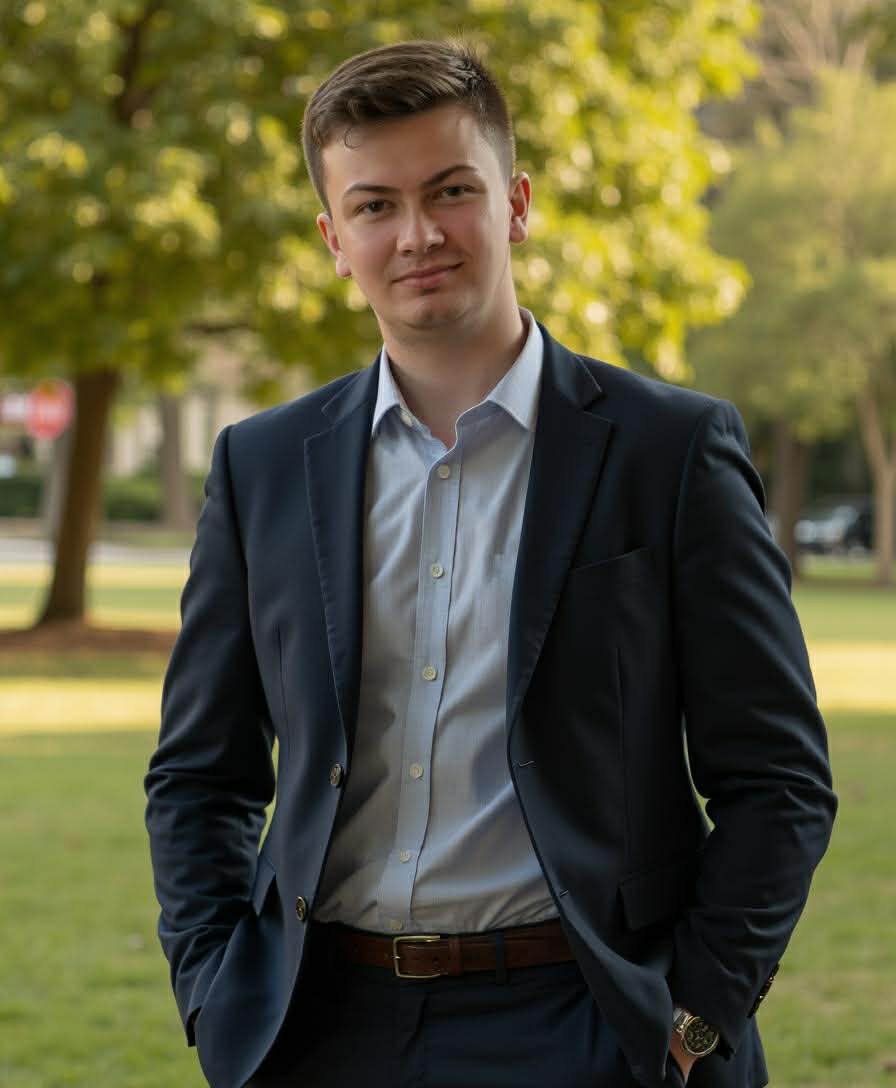
One practitioner. Every file, personally led.
Cody is an Enrolled Agent with an MBA, a solo practitioner with a small support team, working out of Lakeland, Florida.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful. The person who filed your return is the person who handles the IRS.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
How long do I have to respond?
Most CP2000s give you 30 days from the notice date. If you need more time, we file an extension request; the IRS will usually grant another 30. Past 90 days, the notice converts to a statutory notice of deficiency, and your options narrow.
Should I just pay it?
Sometimes. Often not. If the proposed change is correct, a clean payment plus penalty abatement is the right move. If even one line is wrong, paying without contest waives your dispute rights. We tell you which case yours is.
What if I disagree with only part of it?
You file a partial-agreement response. You agree to the lines that are correct, contest the lines that are wrong, and pay only what you owe. That's exactly what we draft.
Can you handle state notices too?
Yes. Florida DOR, Georgia, North Carolina, New York, California — we file the response with the relevant agency. Our authority is federal-EA + state practice rights.
What happens if I ignore the letter?
The IRS assesses the proposed amount as final, accrues penalties and interest, and eventually issues a CP504 or LT11 — at which point your options compress to levy defense. Ignoring it is the most expensive option on the menu.
Will this trigger an audit?
A CP2000 is not an audit. A clean, documented response usually closes the file. A weak response, or no response, is exactly what expands scope.
Related
- IRS representationEvery representation fee published, handled by an Enrolled Agent.
- IRS notice responseAny notice number answered for one flat fee of $600.
- IRS audit representationMail, office and field audits handled, so you don't meet the IRS alone.
- IRS appealsAppeals, CDP hearings, innocent spouse relief and audit reconsideration.
Start the intake. The clock is the issue, not the letter.
Send the form, then pick a time. Have the notice in front of you, and we'll have a response strategy on the call.
Tell us about the letter.
A few questions, then pick a time for a free 15-minute call with Cody. Nothing starts until you sign an engagement letter.
Prefer to talk? Call (863) 370-8115 or Book a 15-minute call.
Form not loading? Open it in a new tab, or call (863) 370-8115.