You moved to Florida.
Your old state has not accepted that yet.
The part-year return in the state you left, your first Florida year, and the record that proves the move actually happened. Prepared by an Enrolled Agent at a published price.
Florida has no personal income tax, which is the entire point of the move. But the state you left is the one that decides whether you left, and New York, California, New Jersey and Illinois all decide it slowly and in their own favor. Keep an apartment up north and spend 184 days there and New York can tax all of your income as a statutory resident, whatever your intent was. Work remotely for a New York employer and the convenience-of-the-employer rule can keep taxing your wages while you sit in Florida. These are audits of where you slept, not of what you earned — and they are won with records you either kept in your first year or did not.
How we fix it.
Map the year
We fix your move date, split the year around it, and list every state with a remaining claim: the one you left, any state where you kept a rental or a business, and any state that sourced a K-1 or a bonus to you. If you moved during 2026, the return you file in spring 2027 is the part-year one. Foreign accounts and crypto are a federal question, not a state one, and we handle those in the same file.
Part-year return built
Income allocated by date and by source, not by estimate. Wages split at the move date, investment income split at the move date, and anything the old state can still source to itself — rental income, a K-1, an equity award granted before you left — reported where it belongs, so you are not audited over a shortcut that was never worth taking.
The domicile file
We hand you the checklist the old state will ask for: a Florida Declaration of Domicile filed with the clerk, a Florida driver's license, vehicle registrations, voter registration, the homestead application, the old state's residency-based exemption formally surrendered, and a day count you can actually produce. Filed and dated beats remembered every time.
Estimates, because nothing is withheld now
No Florida withholding means no cushion under you. On Complete and Concierge we set quarterly federal estimates on the new number so April is not the first time you see it, and we revisit them when the bonus, the vest or the closing lands. Essential files the return; if you want the coming year mapped, that is what Complete buys, and you can move up a tier in the year you need it.
Why us for new Florida residents.
Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make.
183 days is one test. Domicile is a different test. You can fail one and pass the other.
New York taxes you as a statutory resident if you keep a permanent place of abode there and spend more than 183 days in the state — and any part of a day counts as a full day. Domicile is the separate question, decided on the five factors New York actually weighs: your home, your active business involvement, your time, your items near and dear, and your family connections. California uses no day threshold at all; it weighs closest connections. Keeping the old house, and a key to it, is the single most common way people lose this.
Whatever came with you keeps filing where it came from.
A rental you kept in New Jersey files a New Jersey nonresident return. A K-1 from an Illinois partnership sources Illinois income to you in Florida. RSUs and stock options granted before the move are allocated over the workdays between grant and vest, so a New York RSU grant that vests in your third Florida year is still partly New York wages. None of that undoes the move — it just means the return has more than one state on it, and each state beyond the first is a published $100.
Your pension is protected by federal law. Your deferred comp may not be.
P.L. 104-95, at 4 U.S.C. §114, forbids a state from taxing the retirement income of someone who no longer lives there: qualified plans, IRAs, 401(k)s. Nonqualified deferred compensation only gets that protection when it is paid in substantially equal installments over ten years or more, or over life. A lump-sum payout of a nonqualified plan is the trap, and the timing of it is usually still in your hands when you call us early enough.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or start your intake.
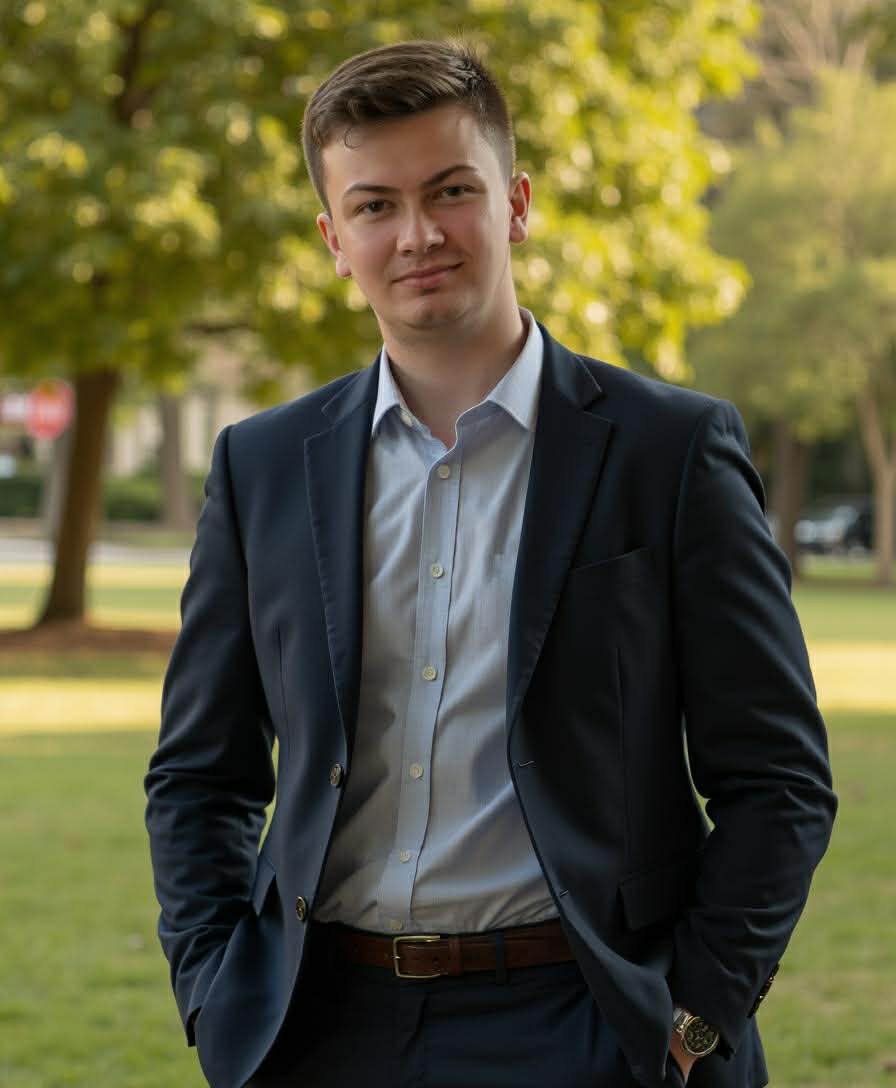
One practitioner. Every file, personally led.
Cody is an Enrolled Agent with an MBA, a solo practitioner with a small support team, working out of Lakeland, Florida.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful. The person who filed your return is the person who handles the IRS.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
When did I actually become a Florida resident?
The day you moved in intending to stay, not the day you got the license. Intent is proved with dates: the closing statement or the lease start, the moving company invoice, the Declaration of Domicile, the driver's license, the vehicle registrations, the voter card, the homestead application. We set one move date and then make every document agree with it, because a file where the dates disagree is the file that gets picked.
Do I still have to file in my old state?
For the year you moved, almost always yes — a part-year return covering the months you lived there, plus anything sourced there afterward. In later years you file a nonresident return only if that state still sources income to you: a rental, a K-1, wages for days you physically worked there, or a convenience-of-the-employer rule. Plenty of new residents file one extra return for one year and then never again.
What is a Declaration of Domicile, and do I need one?
A sworn statement under Florida Statutes §222.17 that you are a Florida resident, naming the state you came from, filed with the clerk of the circuit court in your county. It takes about twenty minutes. It does not by itself end the other state's claim — no single document does — but it is dated, it is sworn, and it is one of the first things asked for. File it, and file it early.
How does Florida homestead work?
Own and occupy the home as your permanent residence on January 1, then apply with the county property appraiser by March 1. The exemption is $25,000 off assessed value, plus a second $25,000 on value between $50,000 and $75,000 that does not apply to school levies, and Save Our Homes then caps annual assessment increases at 3%. You cannot hold a residency-based exemption in another state at the same time — and formally giving that one up is some of the strongest evidence of the move you will ever create. Hillsborough, Orange, Collier, Sarasota, Duval, Polk: same form, same March 1 deadline.
I work remotely for a company in New York. Am I done paying New York?
Not automatically. New York's convenience-of-the-employer rule taxes wages for days you work from home unless the work is performed outside New York for your employer's necessity rather than your own convenience. A few other states apply the same rule. What usually changes the answer is something real on the employer's side — an assigned Florida office, a documented business reason for the location — and that is a conversation to have before the W-2 is issued, not in April after it is.
My old state opened a residency audit. Can you handle it?
Yes, in civil tax matters. Before the IRS that authority is Cody's enrollment as an Enrolled Agent. Before a state revenue department it is that state's own practice rights, which differ by state and which we confirm in writing before we take the engagement rather than after. A residency audit is a separate representation engagement, quoted and paid upfront, never folded into a package and never billed hourly. Start gathering now: the day count, toll and transponder records, credit card statements, cell phone location history, and your calendar. We will tell you what the file looks like before you spend anything on it, and we will not tell you how it is going to come out.
Related
- Individual tax preparationYour household return, one state and investment sales, from $650 a year.
- Real estate taxRentals, short-term rentals, flips and agent commissions.
- Trust and estate tax returnsForm 1041, 706 and 709, with a fixed fee quoted before work starts.
- CRNAs, NPs, locums and travel nursesW-2 or 1099, multi-state work and the entity question.
- Tax planningQuarterly estimates and a written plan before year end, while the moves still count.
Welcome to Florida. Now make the move stick.
Send last year's return, your move date, and a list of what came with you: rentals, K-1s, a business, unvested RSUs or stock options, deferred comp. We map the states and give you the price before you engage. If the mailer, a video or a creator sent you here, mention code NEWFL at intake so we know where you came from.
Tell us about your move.
A few questions, then pick a time for a free 15-minute call with Cody. Nothing starts until you sign an engagement letter.
Prefer to talk? Call (863) 370-8115 or Book a 15-minute call.
Form not loading? Open it in a new tab, or call (863) 370-8115.