§280E, done right. Compliance without overpaying.
We maximize COGS where the code allows it, structure entities to isolate non-280E activities, and prepare returns that survive the audit waiting at the end of every cannabis fiscal year.
§280E disallows nearly every operating expense for cannabis touch-the-plant businesses. The only legitimate offset is properly captured COGS — and COGS done wrong is exactly what the IRS audits. The penalty isn't the audit; it's the years of tax you can't unwind.
How we fix it.
Structure review
Vertical-integration audit. Where can non-280E activities (real estate, IP licensing, hemp) be properly isolated into separate entities?
COGS engineering
§471 inventory rules, full absorption. Direct material, direct labor, allocable indirect — captured at the right cost layer.
State reciprocity
State conformity (or not) to §280E. Many states allow normal deductions; we capture them at the state line.
Audit-ready return
Federal + state, segregated entity returns, detailed COGS workpapers. The audit is a question of when, not if. The return defends itself.
Why us for cannabis operators.
Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make.
COGS optimization under §280E.
Indirect costs allocable to inventory under §471 are deductible as COGS even though they'd be disallowed as opex. Done right, this is often six figures of recovered deductions. Done wrong, it's the audit.
Multi-entity structuring.
Real estate held in a separate LLC. IP licensed from a non-touching entity. Hemp-CBD products in a non-280E sub. Each carve-out, documented, defensible.
State reciprocity to §280E.
Florida, Colorado, Oregon, New York — each state's conformity to §280E varies. Many allow ordinary deductions. We pull every state lever available.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or start your intake.
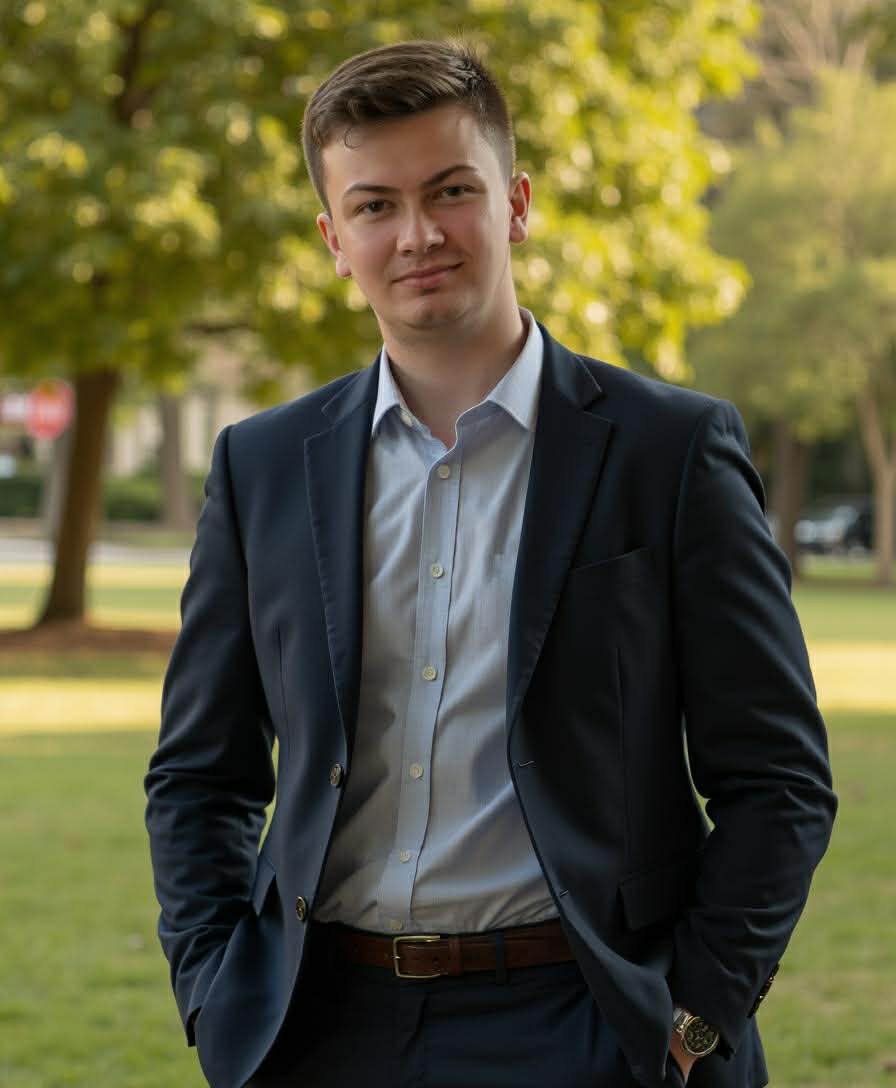
One practitioner. Every file, personally led.
Cody is an Enrolled Agent with an MBA, a solo practitioner with a small support team, working out of Lakeland, Florida.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful. The person who filed your return is the person who handles the IRS.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
Does §280E really mean no deductions?
Almost. Operating expenses are disallowed for businesses 'trafficking' Schedule I/II substances under federal law. COGS, properly captured under §471, is the only material offset.
Will reclassification fix this?
If/when federal scheduling changes, §280E may no longer apply. We position the books so the transition is clean.
Can I split my business?
Yes — provided the split is real. Separate entities, separate books, arm's-length transactions, separate purpose. Champ Capital Holdings is the precedent; we follow it.
How aggressive is the IRS on cannabis?
Very. The federal-state gap puts every legitimate operator at audit risk. We build the return assuming it will be examined.
Multi-state operators?
Common. Each state has different conformity and different filings. We coordinate.
Banking?
We don't bank. We work with the cannabis-friendly bookkeeping and banking integrations our clients already use.
Related
- Business tax preparationS corp, partnership, C corp and Schedule C returns, with the owner's return included.
- Monthly bookkeepingMonthly close and reconciliations from the firm that files your return.
- Tax planningQuarterly estimates and a written plan before year end, while the moves still count.
- Florida sales tax auditsFlorida DOR sales tax audits and protests, starting from the DR-840.
Compliance under §280E. Without leaving COGS on the table.
Send your entity diagram and the last filed return. We'll have a structure read on the call.
Tell us about your business.
A few questions, then pick a time for a free 15-minute call with Cody. Nothing starts until you sign an engagement letter.
Prefer to talk? Call (863) 370-8115 or Book a 15-minute call.
Form not loading? Open it in a new tab, or call (863) 370-8115.