Got an IRS letter?
Tell us about it. We answer it.
Every notice number, one flat fee of $600. An Enrolled Agent reads the notice, pulls your transcripts, files the written response and follows it to the IRS reply.
Every notice carries a date, and the date is the whole problem. Miss the 30 days on a CP2000 and the next letter is a statutory notice of deficiency, whose 90-day clock cannot be extended by anyone for any reason. Miss the 30 days on a final notice of intent to levy and you lose the Collection Due Process hearing that would have suspended the levy. Nothing about the letter gets cheaper while it sits on the counter — penalties and interest accrue daily on an unpaid balance.
How we fix it.
Upload and POA
You upload the notice, your last filed return and a signed Form 2848 through your secure TaxDome portal. No office visit. From there the IRS corresponds with us.
We read the number
We pull your account and wage-and-income transcripts and check the notice against what the IRS actually has. Roughly half of what we see is wrong, partly wrong, or already paid.
Response filed
The written response goes in ahead of the date printed on the notice, with the supporting documents attached and the disputed lines identified one by one.
We follow it
IRS correspondence units run slow. We track the case, answer the follow-up letter, and tell you when the account shows the adjustment.
Why us for IRS notices.
Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make.
Every notice number, one published fee.
CP2000, CP2501, CP11, CP12, CP14, CP501, CP502, CP503, CP504, CP90, CP91, LT11, LT16, LT19, LT38, Letter 1058, Letter 3172, the Form 668 levy notices and the ones with no number at all. The response is $600 flat, quoted and paid upfront, never hourly. If reading the notice shows the real problem is an audit, a collection case or unfiled years, we tell you that before you pay anything.
The deadline is the letter's only real weapon.
A CP2000 gives you 30 days from the notice date. A CP14 gives you 21 days to pay before the account moves further down the collection track. A CP90, LT11 or Letter 1058 gives you 30 days to file Form 12153 and keep your hearing rights. A Letter 3172 gives you 30 days from the fifth business day after the lien was filed. We work backwards from whichever date is on yours.
Civil matters, and no outcome promised.
We represent taxpayers in civil federal tax matters. We are an Enrolled Agent firm, not a law firm. An Enrolled Agent is enrolled to represent taxpayers before the IRS and holds unlimited practice rights before the IRS under Circular 230 — any matter, any IRS office, any tax type, any year. We do not promise a result. What we promise is that the response goes in on time, that it is documented, and that you stop being the one on the phone with the IRS.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or start your intake.
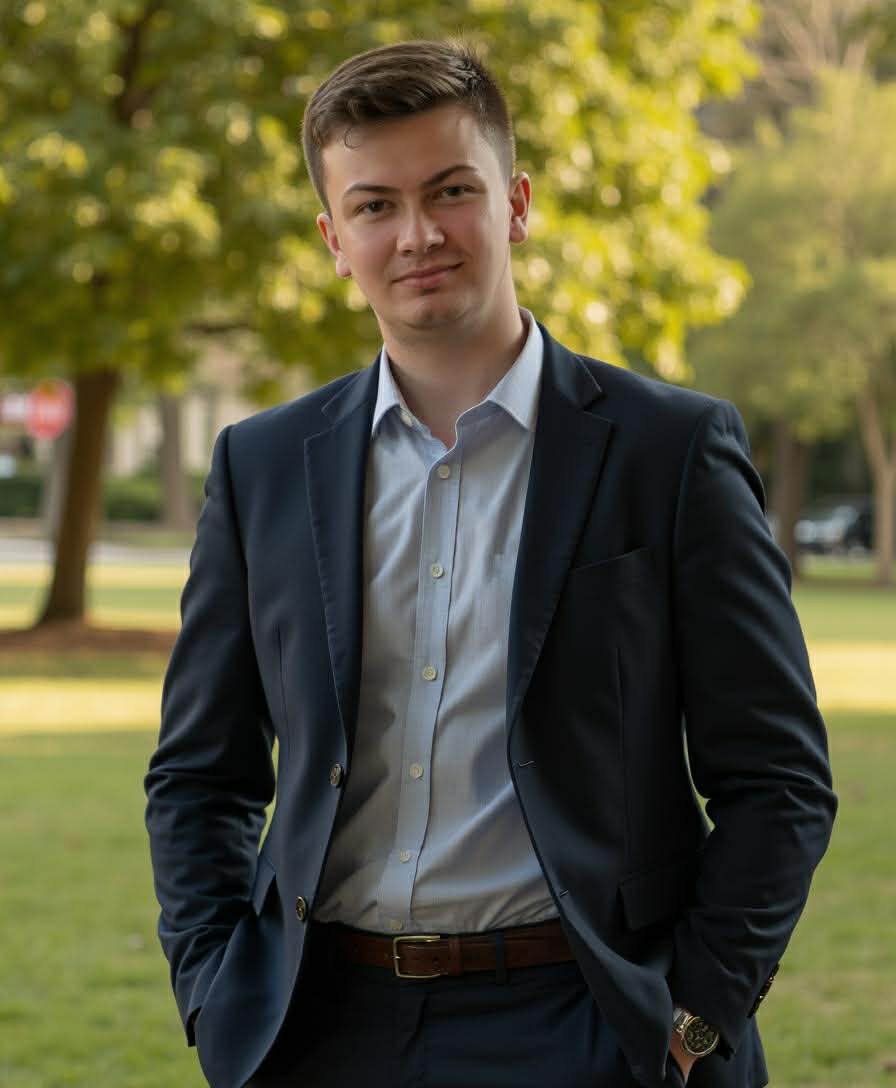
One practitioner. Every file, personally led.
Cody is an Enrolled Agent with an MBA, a solo practitioner with a small support team, working out of Lakeland, Florida.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful. The person who filed your return is the person who handles the IRS.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
CP2000, CP2501 and CP3219A — what are they, and what do you do with them?
A CP2000 is not a bill and not an audit. It is a proposed change because a third party reported something — a 1099, a K-1, a broker statement — that does not match your return, and it gives you 30 days from the notice date. CP2501 is the earlier and quieter version of the same thing: the IRS has seen a mismatch and is asking about it before proposing a number. We pull the wage and income transcript, reconcile it against your records, and file a written response that agrees to the lines that are correct and contests the lines that are not. Partial agreement is a normal outcome and it is what we draft most often. If a CP2000 goes unanswered, what usually follows is a CP3219A or CP3219, the statutory notice of deficiency, and that one starts a 90-day clock that nobody can extend.
CP14, CP501, CP502 and CP503 — the balance-due and math-error notices.
CP14 is the first bill. It means the balance is assessed and interest and the failure-to-pay penalty are running, and we verify the assessment against your transcript before anyone pays it, because misapplied payments and math-error adjustments show up here constantly. CP501 is the first reminder and means the account has entered the automated collection stream; we answer it and, where a payment plan is the right answer, we set one up. CP502 is another reminder in the same series. CP503 is the second reminder and the last quiet one; we put a resolution in front of the IRS before the next notice changes the account status. CP11, CP12, CP15, CP22A, CP22E and CP23 are the math-error and adjustment notices — the IRS changed a figure on your return and recomputed what you owe or what you were getting back. Those are worth checking line by line against the transcript, because an adjustment made automatically is reversed by correcting the record, not by paying it.
CP504, CP90, CP91, LT11 and Letter 1058 — the ones with teeth.
CP504 says the IRS intends to levy your state refund and to look for other assets. It is not yet the final notice, so we respond in writing and move the account into a status that stops the escalation. CP90, LT11 and Letter 1058 are the same thing from three different IRS functions: the final notice of intent to levy, carrying your Collection Due Process right. CP91 and CP298 are the final notice before a levy against Social Security benefits and carry the same right. You have 30 days from the date on any of them to file Form 12153, and filing inside that window suspends levy action while Appeals looks at the case. We file it. On the same track: LT16, LT19 and LT38 are Automated Collection Service letters chasing a balance, LT27 asks for a completed Form 433-F, LT40 tells you the IRS is contacting third parties about your account, CP71 and CP71C are the annual reminder that the balance is still there, and CP523 says an installment agreement is about to be terminated for default. LT18 and LT26 are asking for returns that were never filed, which is the unfiled-returns engagement rather than a notice response, and we will tell you so before you pay for the wrong thing.
Letter 3172 and the Form 668 levies — the lien and the levy.
Letter 3172 is the Notice of Federal Tax Lien Filing and Your Right to a Hearing. The lien is already filed and public when this arrives, and you have 30 days from the fifth business day after filing to request a CDP hearing; we file the request and, where the facts support it, the withdrawal, discharge or subordination application. The levy itself comes on a Form 668, not a letter — Form 668-W goes to your employer and takes part of every paycheck, which is what most people call a wage garnishment, and Form 668-A goes to your bank and freezes the account for 21 days before the money moves. We file the release request inside that 21-day window.
What does the $600 actually cover?
Reading the notice, filing the Form 2848, pulling your transcripts, drafting and filing the written response with its supporting documents, and following the case to the IRS reply. It is quoted and paid upfront and it is never billed hourly. Representation engagements past a notice response — an audit, a collection case, unfiled years — are separate, and every one of them is on the published fee menu before you commit.
Should I just call the IRS myself first?
Usually not. The assistor on the phone cannot change a proposed adjustment, the call is noted on your account, and taxpayers routinely volunteer information about years that were never in question. Once Form 2848 is filed, the IRS deals with us. You can stop opening the mail with your stomach in your throat.
Related
- IRS representationEvery representation fee published, handled by an Enrolled Agent.
- CP2000 noticesThe IRS thinks you left income off. We check it before you pay.
- IRS audit representationMail, office and field audits handled, so you don't meet the IRS alone.
- IRS payment plans and collectionsPayment plans, hardship status and levy releases, with the option you qualify for.
Send the form. $600 flat, and you stop reading IRS mail.
Send the form with the letter's number and date, then pick a time. We will tell you what the number and the date mean before you pay anything.
Tell us about the letter.
A few questions, then pick a time for a free 15-minute call with Cody. Nothing starts until you sign an engagement letter.
Prefer to talk? Call (863) 370-8115 or Book a 15-minute call.
Form not loading? Open it in a new tab, or call (863) 370-8115.