A DR-840 landed.
Call before you reply.
Florida Department of Revenue audits, assessments and protests: sales and use tax, reemployment tax, commercial rent tax and tourist development tax. Flat fee, quoted upfront. This is state tax practice, not IRS representation, and we keep the two labeled.
A Florida sales tax audit is a projection, not a count. The Department picks a sample period, tests it, and applies the error rate it finds across the whole audit period — so one badly documented quarter becomes three years of assessed tax with penalty and interest on top. Tax you collected from customers and did not remit is treated differently from tax you simply failed to charge: Florida can pursue it personally against the officers and directors who had control of the money, and an unpaid assessment becomes a warrant and a lien.
How we fix it.
Read the DR-840
Send the form the day the notice arrives, and upload the notice to your secure TaxDome portal after the call. No office visit, and no call to the Department first. The Notice of Intent to Audit Books and Records starts a 60-day period before the audit may begin. That window is the most valuable thing you will get in this case, and it is usually spent badly.
The sample is negotiated
What period gets sampled, which records are in scope, and how the projection is calculated are all agreed in writing at the start. That agreement, not the fieldwork, is where most of the assessment is decided.
Records go in organized
Exemption certificates reconciled, resale documentation matched to the invoices, fixed-asset purchases separated from use tax exposure, POS data tied back to the filed DR-15s. The auditor works from our schedule, not your shoebox.
Respond, then protest
The Notice of Intent to Make Audit Changes gives you a short window to answer the work papers before the assessment is proposed. If the Notice of Proposed Assessment still comes, we file the written protest.
Why us for Florida DOR audits.
Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make.
The DR-840 and the 60 days it buys you.
The Notice of Intent to Audit Books and Records is not the audit. Florida cannot begin the audit for 60 days after it is issued, and that time exists so a business can get its records straight and, where something is genuinely wrong, address it before the auditor arrives. Most businesses either call the Department and start answering questions or do nothing at all. Both waste the window. Call before you reply to it.
Sample-period audits: one bad month becomes three years.
The Department rarely examines every transaction. It agrees a sampling method with you in writing, tests a period, computes an error rate and projects that rate across the full audit period. That means a single missing exemption certificate in the sample month can be multiplied by thirty-six. Which months, which transactions and which method get used are negotiable at the start and are effectively fixed afterwards. This is the part of the case worth spending money on.
Warrants, liens and your certificate of registration.
An unresolved assessment becomes a tax warrant, which is recorded and attaches as a lien against your property, and the Department can also proceed against your certificate of registration through a revocation process — which is the end of legally making taxable sales in Florida. Where tax was collected from customers and not remitted, Florida law reaches the individuals who had the duty and authority to remit it, so the exposure does not necessarily stop at the company.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or start your intake.
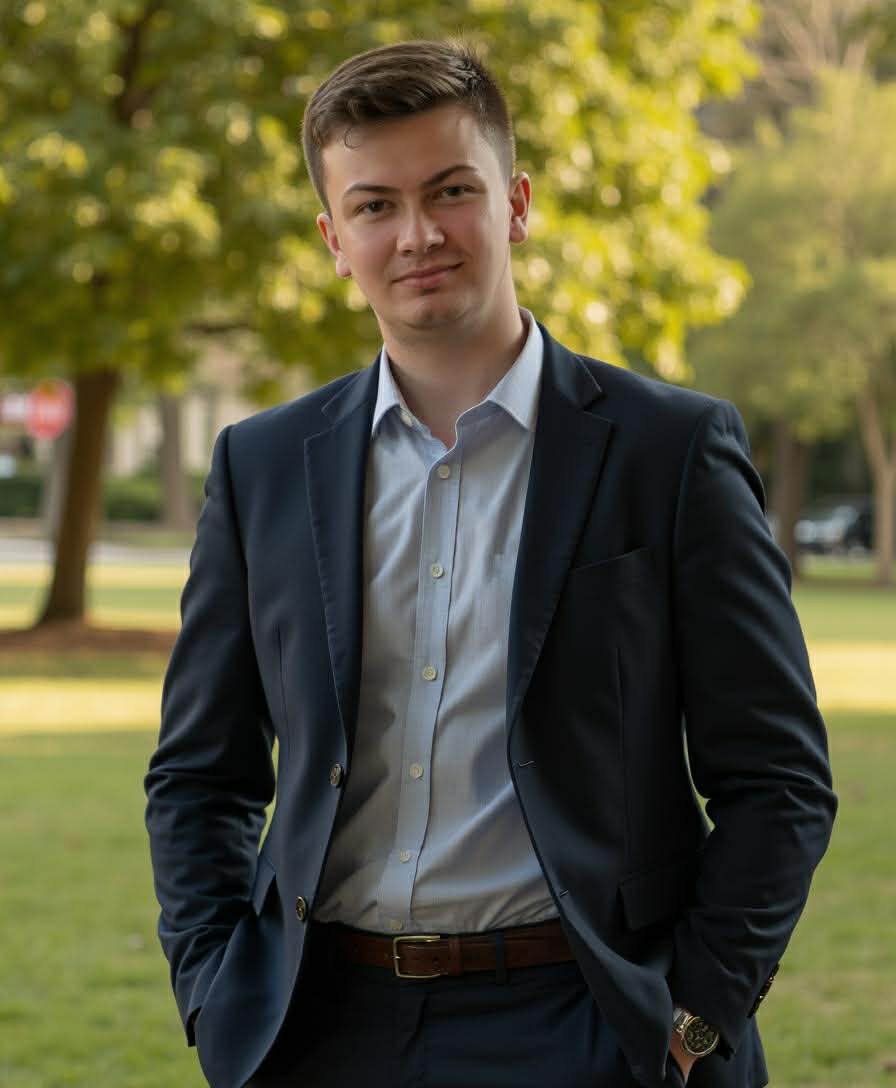
One practitioner. Every file, personally led.
Cody is an Enrolled Agent with an MBA, a solo practitioner with a small support team, working out of Lakeland, Florida.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful. The person who filed your return is the person who handles the IRS.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
What exactly is a DR-840?
The Notice of Intent to Audit Books and Records. It tells you which tax type, which period and which auditor, and it starts a 60-day clock during which the Department may not begin the audit. It is also the document that stops you from fixing certain things quietly, so the order of operations from here matters. Send it to us before you respond to it.
How does the sampling actually work?
You and the Department agree a sampling method in writing — which months, which transaction types, and how the results get projected. The auditor tests the sample, computes an error rate, and applies it across the whole audit period. Because the projection multiplies everything, a documentation gap in a sampled month is worth far more than the transaction itself. Negotiating the sample well is most of this engagement.
Which businesses does the Florida DOR audit most?
Restaurants and bars, convenience stores and gas stations, used car and boat dealers, construction contractors, auto repair, commercial landlords, vending operators, marinas, and short-term and vacation rental operators. If you take cash, sell across an exemption line, or file a DR-15 with numbers that move against your industry pattern, you are in the population. It is also worth knowing the Department audits more than sales and use tax. Commercial rent tax is the sales tax charged on rent for commercial real property, which is why commercial landlords are on that list. Tourist development tax is the transient rental tax on short stays, which is why vacation rental operators are. Reemployment tax audits are a different question again: they test whether the people you paid on a 1099 should have been on the RT-6 as employees, and a reclassification there produces back tax across open quarters. All three run on the same DR-840 notice, the same negotiated sample period and the same projection, so the defense is the same work at the same fee.
I collected the tax but could not remit it. How bad is that?
It is the serious version. Florida distinguishes tax you failed to charge from tax you charged your customers and kept, and for the second category the Department can pursue the individuals who had the authority and duty to remit it, not only the business. It is also the category where a resolution has to be built carefully and early. Do not let this one sit.
Can they revoke my sales tax certificate?
The Department can move to revoke a certificate of registration where a business fails to comply, and there is a process with a conference before it happens. It can also record a tax warrant, which attaches as a lien and can lead to levy. Both are avoidable outcomes, and both are far easier to avoid before the assessment becomes final than after.
Is this the same as IRS representation?
No, and we keep it labeled. Enrollment as an Enrolled Agent is a federal credential: it carries unlimited practice rights before the IRS under Circular 230, and it says nothing at all about Tallahassee. Florida Department of Revenue work is state tax practice, handled under Florida's own rules for who may represent a taxpayer before the Department. We do both, we price them separately, and we do not blur the two on a bill or on a page. If a DOR audit turns up a federal problem, that is a separate engagement with its own quote.
Related
- Business tax preparationS corp, partnership, C corp and Schedule C returns, with the owner's return included.
- S corp tax servicesWhether the election pays, Form 2553, a salary you can defend, and the 1120-S.
- Tax planningQuarterly estimates and a written plan before year end, while the moves still count.
- Monthly bookkeepingMonthly close and reconciliations from the firm that files your return.
- PayrollPayroll run, taxes deposited and filed, W-2s and Florida reemployment tax.
Do not answer the DR-840 yet. You have 60 days and they are worth something.
Send the form, then pick a time. Have the notice, your last twelve DR-15s and a rough monthly sales figure ready for the call, and we will tell you what the sample is likely to cost you.
Tell us about the audit notice.
A few questions, then pick a time for a free 15-minute call with Cody. Nothing starts until you sign an engagement letter.
Prefer to talk? Call (863) 370-8115 or Book a 15-minute call.
Form not loading? Open it in a new tab, or call (863) 370-8115.