You owe the IRS.
Here are the five real options.
Installment agreements, offers in compromise, hardship status, levy and lien work. We tell you what you actually qualify for, at a fee published before you commit. We are not a tax relief company.
Interest and the failure-to-pay penalty run daily on an unpaid balance, and the account keeps moving down the collection track whether or not anybody answers the mail. Automated collection escalates to a final notice, a final notice becomes a wage levy or a bank levy, and a bank levy freezes the account for 21 days and then sends the money. If a revenue officer has been assigned — individual cases get them too, not only payroll cases — the file is out of the automated stream and in front of a person who sets the deadlines, asks for financials on a date they choose, and can levy without another round of letters. That is the point to have representation, not after the first meeting. The difference between an expensive problem and an emergency is usually just how long the notices sat unopened.
How we fix it.
POA and transcripts
You upload the notices and a signed Form 2848 to your secure TaxDome portal. No office visit. The POA goes in and we pull the full account transcript, so we know the real balance by year, which years are assessed, and where the collection statute stands on each one.
The financial picture
For anything beyond a streamlined plan we build the Form 433 financial statement — 433-A for an individual, 433-B for a business, 433-F for the short form Automated Collection asks for — against the IRS allowable living expense standards. That statement decides which of the options you actually qualify for.
The option goes in
Installment agreement, offer in compromise, currently not collectible, penalty abatement — or a levy release first if money is already moving. Filed with documentation, not a phone call.
Holding it in place
Agreements default when a new year goes unfiled or an estimated payment is missed. We put the compliance calendar in place that keeps the resolution alive.
Why us for IRS collections.
Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make.
The five options, and who honestly qualifies for each.
A streamlined installment agreement needs a balance inside the IRS streamlined threshold and no financial statement. It is requested on Form 9465 and our fee for it is $750. A non-streamlined agreement means a Form 433 financial statement and a monthly payment negotiated against the IRS allowable expense standards. Our fee for it is $1,500. A partial payment installment agreement is that same engagement at that same $1,500 — it is the version for a balance the agreed payments will not clear before the collection statute expires, and the IRS reviews it periodically to see whether you can pay more. An offer in compromise is for people whose reasonable collection potential is genuinely less than the balance, $3,500. Currently not collectible is for people whose income barely covers allowable living expenses, $1,000. Penalty abatement is first-time at $400 or a written reasonable-cause request on Form 843 at $900. Which one fits is arithmetic, not salesmanship.
A levy and a lien are two different problems.
A levy takes property. Form 668-W goes to your employer and takes part of every paycheck until it is released, which is what most people mean when they say the IRS is garnishing their wages; a wage garnishment and a wage levy are the same thing and a release is the same filing either way. Form 668-A goes to your bank and freezes the account for 21 days before the funds are sent, which is the whole window you get to act in. A lien is a public claim against what you own; it does not take anything today, but it follows you into a closing or a refinance. Levy release is $1,000, and lien withdrawal, discharge or subordination is $1,000. Releasing one does nothing to the other.
Fresh Start is an IRS program, not a discount.
Fresh Start is the name for a set of IRS collection policy changes — higher streamlined agreement thresholds, easier lien withdrawal, adjusted offer calculations. It is not a settlement program, and nobody can enroll you in it. Most people who are sold an offer in compromise do not qualify for one, and the IRS rejects a large share of the offers it receives. If your numbers do not support an offer, we will tell you that on the first call instead of taking a fee to find out slowly.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or start your intake.
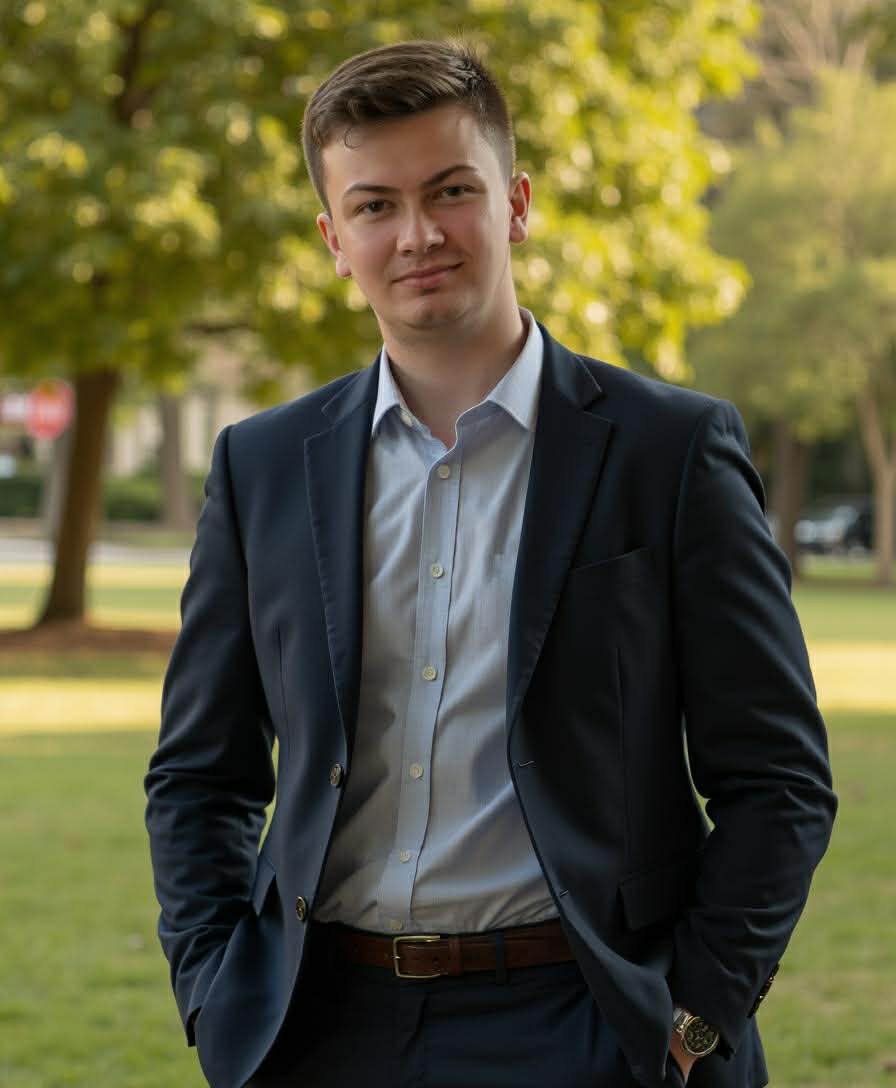
One practitioner. Every file, personally led.
Cody is an Enrolled Agent with an MBA, a solo practitioner with a small support team, working out of Lakeland, Florida.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful. The person who filed your return is the person who handles the IRS.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
Do I qualify for an offer in compromise?
Probably not, and that is the honest answer for most people who ask. The IRS compares your equity in assets plus your future income over a set number of months against the balance. If that figure exceeds what you owe, the offer gets rejected and you have spent the money and the time. We run the calculation first. When the numbers do work, the offer is a genuinely good outcome and we file it at a published $3,500.
What is Fresh Start, and can you get me into it?
Nobody gets you into it. Fresh Start is a set of IRS collection policy changes that raised streamlined installment agreement limits, made lien withdrawal easier and adjusted how offers are calculated. Every eligible taxpayer already gets the benefit of it through the normal process. Any firm selling access to it is selling the process itself.
My bank account is frozen. How long do I have?
21 days. A bank levy on Form 668-A freezes the funds that were in the account when the levy was served and the bank holds them for 21 days before sending them to the IRS. That window is the entire opportunity. Call the same day — this is the one thing on this page that genuinely cannot wait.
What is currently not collectible status?
It is a hardship determination. You document income and allowable living expenses on a Form 433, and where the numbers show you cannot pay anything without falling short of basic living expenses, the IRS codes the account as not collectible and stops active collection. Interest keeps running, the IRS reviews it when your income changes, and a lien may still be filed. For people in a genuinely bad year it is the most useful and most underused option on the list. It is $1,000.
Can the penalties come off?
Sometimes. First-time abatement is administrative relief for taxpayers with a clean prior compliance record and it is $400 to prepare and file. Reasonable cause is a written argument with documentation — serious illness, a death in the family, records destroyed, reliance that was genuinely reasonable — filed on Form 843, the claim for refund and request for abatement, and it is $900. Form 843 is also how a penalty you have already paid gets claimed back. Interest on the tax itself is statutory and almost never abated.
Are you a tax relief company?
No. Ring Tax is an Enrolled Agent firm in Lakeland serving all of Florida, enrolled to represent taxpayers before the IRS, with unlimited practice rights there under Circular 230 — the same representation rights a CPA or an attorney has. Tax is all we do, and that cuts both ways: audited and reviewed financial statements are attest work, which only a CPA can perform, and we do not do them or claim to. There is no call center, no case manager who is actually a salesperson, and no pennies-on-the-dollar promise. You get a published flat fee, a real qualification answer, and the same practitioner on the file from the first call to the close.
Related
- IRS representationEvery representation fee published, handled by an Enrolled Agent.
- Offer in compromiseSettling for less, only when the numbers really support it.
- Wage garnishment, liens and leviesStopping a garnishment or bank levy, starting the day you call.
- Unfiled tax returnsWe pull your IRS records and file the missing years, quoted at intake.
Tell us the balance. We will tell you which of the five you qualify for.
If a levy is already running, call — a bank levy gives you 21 days and not one more.
Tell us what you owe.
A few questions, then pick a time for a free 15-minute call with Cody. Nothing starts until you sign an engagement letter.
Prefer to talk? Call (863) 370-8115 or Book a 15-minute call.
Form not loading? Open it in a new tab, or call (863) 370-8115.