S-Corp election,
done right — and worth it.
We model the savings, file the election, set reasonable compensation, and handle the 1120-S every year. Nothing falls through the cracks.
Botched late elections that get rejected. IRS reclassification of distributions as wages, with payroll-tax penalties stacked on top. Blown S-Corp status from a missed deadline you didn't know existed.
How we fix it.
Breakeven model
We run your actual net profit through the math — payroll cost, state taxes, retirement contribution mix — and confirm the election is worth it.
Form 2553 filed
Election filed with the IRS. Where eligible, we backdate using Rev. Proc. 2013-30 late-election relief. State follow-on filings handled.
Reasonable comp memo
A written, defensible salary analysis tied to your role and market data. Lives in the file in case the IRS asks.
Annual operations
1120-S, K-1s, quarterly payroll (941), annual 940, W-2s. Same firm, every year. Nothing dropped.
Why us for S-Corp owners.
IRS Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make. Currently in law school.
When the S-Corp math actually works.
There's a real threshold (income vs. administrative cost) and a real cliff (too low and you lose the QBI deduction). We model both before we recommend the election.
Reasonable compensation — defensible, not theoretical.
The IRS reclassifies distributions to wages when the salary looks too low for the work. Our memo benchmarks your role to BLS and industry data, in writing, before any audit ever asks.
Late S-Corp election relief — Rev. Proc. 2013-30.
Missed the March 15 deadline? Often you can still elect retroactively to January 1 under the safe-harbor procedure. We've filed dozens. The IRS approves most of them.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or get your price in a minute.
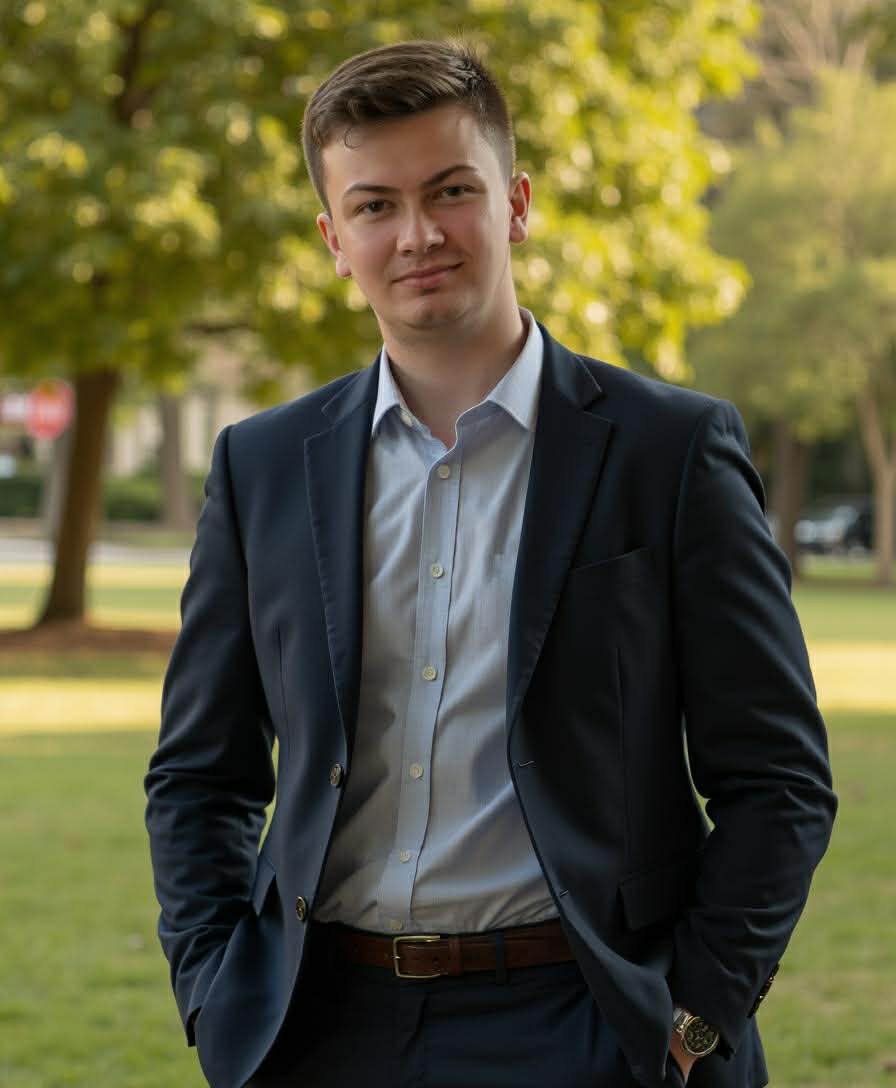
One practitioner. Every file, personally led.
Cody is an IRS Enrolled Agent with an MBA — a solo practitioner with a small support team, working out of Lakeland, Florida. He is also currently in law school.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful — and so when the IRS calls, the person who picks up is the person who filed your return.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
Do I make enough to be an S-Corp?
Usually yes once net profit is consistently past $80K to $100K and steady. Below that, the payroll, state filings, and administrative cost typically outweigh the SE-tax savings. We run your real numbers.
What's reasonable compensation?
A salary the IRS would expect for similar work in your market, paid as W-2 wages. We benchmark it to BLS data and industry sources, and document it in writing. That memo is your audit defense.
Can I elect it for a prior year?
Often, yes — Rev. Proc. 2013-30 provides safe-harbor late-election relief. We file the request with the IRS; the agency approves most well-documented requests.
What's the ongoing cost?
Your 1120-S and your household return sit in one package: $2,850 a year on Essential, $5,350 on Complete, half at engagement and half before filing. Payroll and books live on Concierge, which is $6,100 a year plus $675 a month for one entity, and volume past the included allowances moves to a published monthly band. Compare that to the SE-tax savings on your actual distribution; for most owners the math is decisive.
What if I have multiple businesses?
We can structure separate S-Corps, a holding company, or a parent-subsidiary stack — depends on liability, payroll, and state tax considerations. Common, and solvable. Each additional entity return is a published $2,275, so you know the fee before you form anything.
What about the QBI deduction?
S-Corp wages reduce the QBI base. Sometimes meaningfully. Our model accounts for this — there's a sweet spot, and we find yours.
Related
- Business tax preparationS corp, partnership, C corp and Schedule C returns, with the owner's return included.
- Tax planningQuarterly estimates and a written plan before year end, while the moves still count.
- Monthly bookkeepingMonthly close and reconciliations from the firm that files your return.
- PayrollPayroll run, taxes deposited and filed, W-2s and Florida reemployment tax.
- Florida sales tax auditsFlorida DOR sales tax audits and protests, starting from the DR-840.
Run the breakeven. The number either decides it, or it doesn't.
Bring your YTD P&L (or a rough net-profit number) and we'll show you what the election is actually worth.