Plan it in the off-season.
Save it in April.
Quarterly estimates, a written plan before year end, the S corp election and the reasonable compensation that has to stand behind it. Filed and documented by an Enrolled Agent firm.
April is a report, not a decision. Every move that changes the number had to happen before December 31: the election, the salary, the retirement contribution, the equipment. Miss the March 15 election deadline and you either wait a year or ask the IRS for relief. Underpay the quarters and the penalty is computed on each one separately, whatever the April balance turns out to be.
How we fix it.
The three real numbers
Last year's return, a year-to-date P&L, and what you actually take out of the business. Nothing about entity selection or salary is decidable without all three, and no honest answer comes before we have them.
Election, if it earns its keep
We run the breakeven against payroll cost, state filings and the hit to the QBI deduction. If it clears, we file Form 2553 for the current year. If the date has passed, late election relief under Rev. Proc. 2013-30 is usually still on the table and we file that instead.
Estimates, recalculated
April 15, June 15, September 15 and January 15, computed off year-to-date numbers instead of last year's. When a large month lands or a property sells, the next payment moves before the quarter closes.
The written plan
A dated list of moves with the dollar effect of each: reasonable compensation set and actually paid through payroll, retirement plan funded, accountable plan reimbursements run, equipment timed. You decide what to do. The plan is in writing either way.
Why us for owner tax planning.
IRS Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make. Currently in law school.
Reasonable compensation, written down before anyone asks for it.
The IRS reclassifies distributions as wages when the salary looks too low for the work being done. We benchmark your role against market pay data, set a defensible figure, and keep the memo in the file. An S corp with no salary and no memo is the easiest adjustment an examiner will make all year.
The election is a math problem, not a status symbol.
Payroll filings, state registration and the reduction in the QBI base are real costs. For most owners the election starts paying once net profit is consistently past $80K to $100K and steady. Below that we tell you to wait, and we put the reason in writing so you can revisit it next year instead of re-litigating it.
Retirement and entity decisions belong in the same conversation.
For an S corp owner a solo 401(k) deferral comes out of a W-2 paycheck, so the plan has to exist and the deferral election has to be made before the last payroll of the year. A SEP can usually be opened and funded later, after the year is closed. Which one wins depends on the salary we just set, so we decide both at once instead of discovering the conflict in April.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or get your price in a minute.
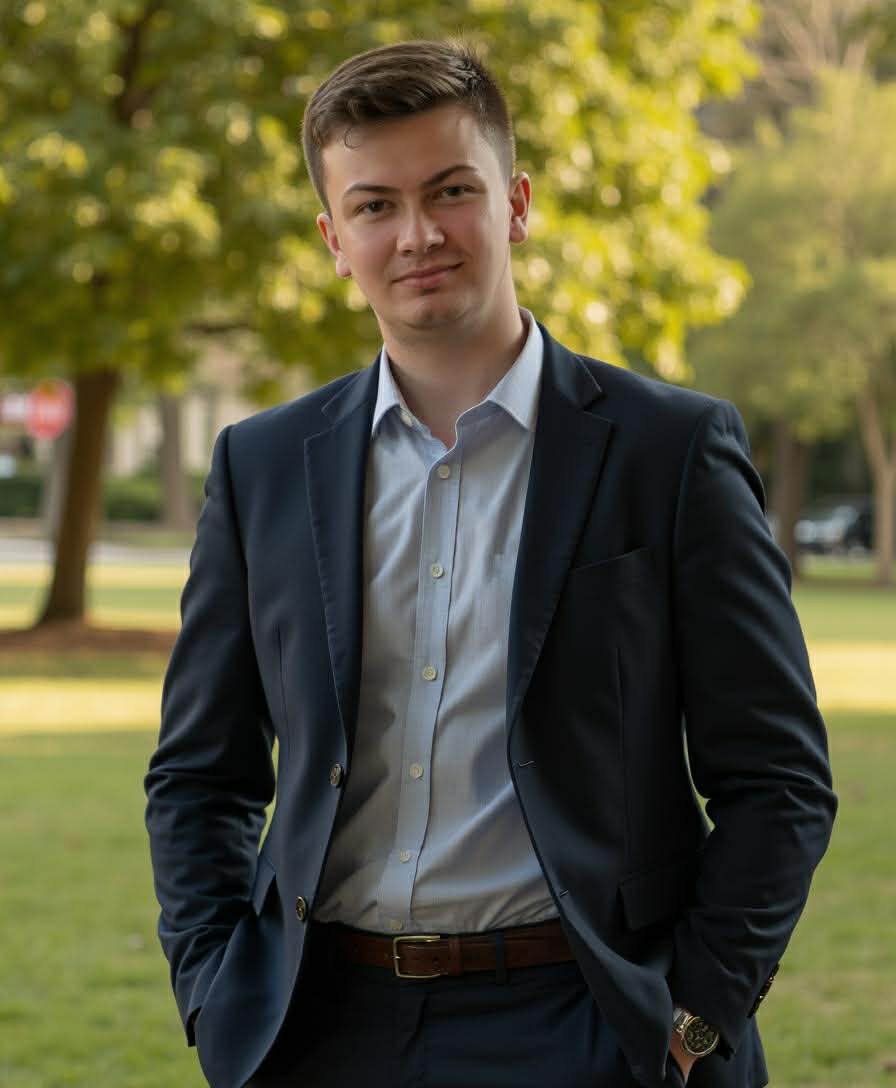
One practitioner. Every file, personally led.
Cody is an IRS Enrolled Agent with an MBA — a solo practitioner with a small support team, working out of Lakeland, Florida. He is also currently in law school.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful — and so when the IRS calls, the person who picks up is the person who filed your return.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
When does planning actually have to happen?
July through December for the year you are in. By the time you are signing the return, the year is closed and the only thing left is reporting it. The one date that sits earlier is the S corp election: March 15 for a calendar-year entity that wants the election effective for the current year.
How much salary do I have to pay myself?
Enough that the IRS would call it reasonable for the work you do, in your market. We benchmark it, document it in a memo, and run it through real payroll with 941s and a W-2 at year end. A number picked because it sounded low is the one that gets adjusted, with payroll tax and penalties stacked behind it.
I missed March 15. Is the election dead for this year?
Usually not. Rev. Proc. 2013-30 provides late-election relief, often retroactive to January 1. We file the Form 2553 with the relief language on it and a reasonable-cause statement attached, and we keep the facts behind that statement in the file. Relief is discretionary. Nobody can promise the IRS will grant yours, and we will not.
Is an LLC taxed as an S corp still an LLC?
Yes. The LLC is the legal entity your state registered; S corp is a federal tax classification you elect on top of it. Your operating agreement, your bank account and your liability protection do not change. What changes is that you now run payroll, file an 1120-S and take the rest as distributions.
What does planning cost on its own?
The entry point is Individual Complete at $2,150: quarterly estimates, a written plan before year end, one projection a year, and the return itself. With a Schedule C it is $2,450 and with an entity $5,350, and Concierge adds a mid-year review on top of the annual plan. We do not sell a planning session on its own, because the plan only works when the same firm files the return and can see whether the moves actually landed.
Do the strategies people ask about by name actually work?
Some of them, for some people. An accountable plan reimbursement is routine and we set it up. Paying your children works when the work is real, documented and paid at a defensible rate. The Augusta rule works for a genuine business meeting at a defensible rent, with minutes. Cost segregation works on the right building, and we coordinate the engineering study rather than pretend we perform it. We will tell you which of these fits you and which one belongs to somebody else's video.
Related
- Business tax preparationS corp, partnership, C corp and Schedule C returns, with the owner's return included.
- S corp tax servicesWhether the election pays, Form 2553, a salary you can defend, and the 1120-S.
- Monthly bookkeepingMonthly close and reconciliations from the firm that files your return.
- PayrollPayroll run, taxes deposited and filed, W-2s and Florida reemployment tax.
- Florida sales tax auditsFlorida DOR sales tax audits and protests, starting from the DR-840.
Bring the year-to-date number. We will tell you what it is worth.
Last year's return, a YTD P&L and what you take out of the business. That is enough to run the election math and start the plan.