Being audited?
Do not call the IRS first.
Enrolled Agent representation for mail, office and field examinations — unlimited practice rights before the IRS under Circular 230, the same rights a CPA has, at a flat fee you see before you call. Form 2848 filed on day one, and the auditor deals with us. Civil matters only.
Audits expand through conversation. A correspondence exam about one Schedule C line becomes an office exam about three years because someone answered a friendly question about the other business. The examiner's job is to develop issues; yours is not to hand them over. Scope is decided in the first two weeks and it is very hard to narrow again afterwards.
How we fix it.
POA filed
You upload the letter and a signed Form 2848 through the secure portal. No office visit. The POA goes in and the IRS recognizes representation, and from that point the examiner contacts us, schedules with us, and sends the document requests to us.
Scope read
We read the letter against your transcripts and identify exactly which line items, which entity and which year are actually under examination. Nothing outside that gets discussed.
We answer, you work
Correspondence audits are answered in writing. For an office or field exam we attend; Form 2848 means you usually do not have to. Documents go in organized, indexed and limited to what was asked for.
Agree or appeal
No change, an agreed adjustment, or unagreed and on to Appeals. We do not sign off on bad math because the examiner wants the file closed.
Why us for IRS audits.
IRS Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make. Currently in law school.
Mail, office and field are three different examinations.
A correspondence audit (Letter 566, CP75) is paper only and usually one or two issues; representation is $1,500. An office audit (Letter 3572) is an appointment at an IRS office, broader, and with an examiner sitting across the table; a field audit (Letter 2205) sends a revenue agent to your home or business and is open-ended. Office and field are both $3,500. A business examination of an S corp, partnership or employment tax return is $5,000.
Do not call the IRS first.
The examiner is building a file from the moment of first contact, and everything you say in that call is in it. Taxpayers volunteer adjacent years, mention the other business, explain a deduction they were never asked about. Once the Form 2848 is filed, none of that can happen by accident.
Form 2848, and the credential standing behind it.
Form 2848 is the IRS power of attorney. It names the tax form, the tax type and the specific years we are authorized for, and nothing else. It lets us receive notices, talk to the examiner and sign agreements you approve. It does not give us access to your bank accounts and it does not make us liable for your tax. You can revoke it in writing at any time. The person it names is an Enrolled Agent, enrolled to represent taxpayers before the IRS and holding unlimited practice rights before the IRS under Circular 230 — the same right to stand in an examination that a CPA or an attorney has. Tax is all we do. Audited and reviewed financial statements are attest work, which only a CPA can perform; we do not do them and we do not claim to.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or get your price in a minute.
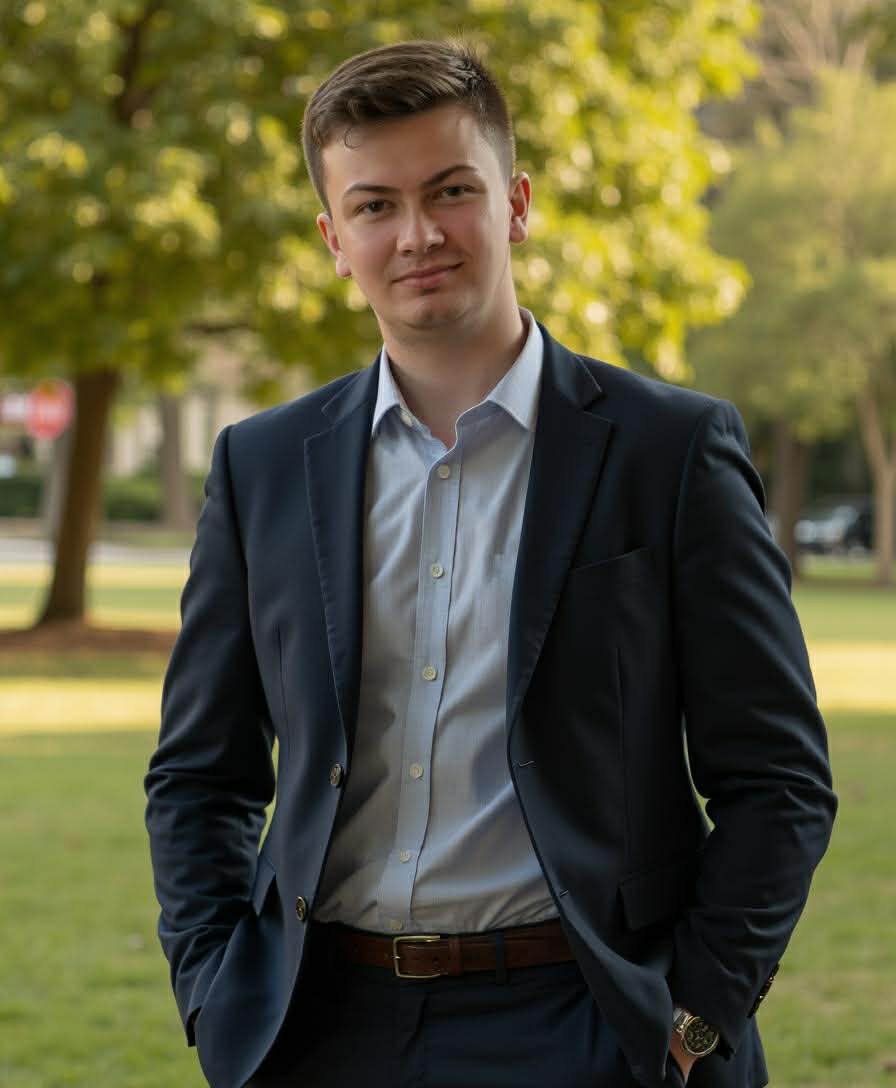
One practitioner. Every file, personally led.
Cody is an IRS Enrolled Agent with an MBA — a solo practitioner with a small support team, working out of Lakeland, Florida. He is also currently in law school.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful — and so when the IRS calls, the person who picks up is the person who filed your return.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
Which letter did I get?
Letter 566 and CP75 are correspondence examinations, usually about the earned income credit, dependents, or one line on a Schedule C or Schedule A. Letter 2202 and Letter 3572 schedule an office examination. Letter 2205 is the opening letter for a field examination by a revenue agent. An Information Document Request is Form 4564, and the examiner's findings arrive as a revenue agent report with Form 886-A, the explanation of items, attached. Letter 525 and Letter 950 are the 30-day letters: the examination is finished, you disagree, and you have 30 days to file a written protest with IRS Appeals. Letter 692 is the shorter-window request to consider additional findings. Letter 531 and Letter 3219 are the statutory notice of deficiency, and that is the 90-day clock nobody can extend. Upload whichever one you got and we will tell you which track you are on.
What kinds of returns do you defend?
Schedule C sole proprietors, rental property owners, crypto and trading accounts, unreported income cases, and small business returns — S corps, partnerships and employment tax. Those are the examinations this office sees week in and week out.
Do I have to be there?
For a correspondence audit there is nothing to attend. For an office or field examination, Form 2848 lets us appear without you, and most clients never meet the examiner. Where the agent genuinely needs to see the premises on a field exam, we are there with you and we do the talking.
What if I do not have the receipts?
A deduction can often be substantiated with indirect evidence — bank and card statements, calendars, mileage logs, vendor histories, contemporaneous notes. Certain categories are held to strict substantiation and cannot be reconstructed that way. We tell you which of your lines fall in which bucket before we put anything in front of the examiner.
Can the audit expand to other years?
It can. The examiner can pick up prior or subsequent years when the same issue appears in them. Keeping the exam on the years and issues in the letter is most of what this engagement actually is.
What if the examiner and I still disagree at the end?
Then the case goes unagreed and you have the 30-day letter, which is your invitation to file a written protest with IRS Appeals. Appeals is a separate function with a different mandate, and an Enrolled Agent has unlimited practice rights there. That engagement is a published $2,500.
Related
- IRS representationEvery representation fee published, handled by an Enrolled Agent.
- IRS appealsAppeals, CDP hearings, innocent spouse relief and audit reconsideration.
- IRS notice responseAny notice number answered for one flat fee of $600.
- CP2000 noticesThe IRS thinks you left income off. We check it before you pay.
Upload the letter before you answer it. The first two weeks decide the scope.
Form 2848 filed within 24 hours of intake. From there the examiner calls us, not you.