Haven't filed in years?
No judgment. Just filing.
We pull your IRS record, rebuild the years that are missing, and file them, for a fixed fee quoted at intake before any work starts.
When you do not file, the IRS eventually files for you. A substitute for return uses the income third parties reported and gives you no business expenses, no basis on a stock sale, no dependents and the filing status that produces the largest balance. That assessment becomes real tax, and it collects like any other. Refunds have their own clock: a refund you were owed expires three years after the original due date and does not come back.
How we fix it.
We pull the record
You upload whatever you have to the secure portal — a signed Form 2848, any notices, whatever records survived. No office visit, and an incomplete pile is normal. Then we pull the account transcript and the wage and income transcript for every open year, which tells us which years are missing, which the IRS filed for you, and what the agency thinks you owe today.
The years get rebuilt
We reconstruct from the transcripts, bank statements, prior schedules and whatever you still have, then prepare and file the returns — normally the last six years, which is the IRS compliance window.
The balance
Filing usually lowers the number, sometimes to nothing. Whatever is left goes into an installment agreement, currently not collectible status, or an offer where the math supports one.
Stay filed
Current-year preparation, quarterly estimates where you need them, and a calendar. Every collection resolution defaults the moment a new year goes unfiled.
Why us for unfiled returns.
IRS Enrolled Agent, enrolled to represent taxpayers before the IRS in all 50 states, alongside CPAs and attorneys.
Finance training: the math behind every recommendation we make. Currently in law school.
We pull your IRS record before you guess at anything.
Once Form 2848 is filed we request the wage and income transcript, which lists every W-2, 1099, 1098, K-1 and broker statement reported under your number for that year, and the account transcript, which shows assessments, substitute returns, payments and where the collection statute stands. An Enrolled Agent holds unlimited practice rights before the IRS under Circular 230, so from the moment that POA is on file the agency deals with us and not with you. You do not have to remember who you worked for in 2019. The IRS already wrote it down.
Six years is the compliance window.
IRS policy is that filing the last six years generally brings a non-filer back into compliance, and that is what we file unless something specific in your record says otherwise — a fraud referral, an open examination, or a refund year worth reaching for. There is no statute of limitations on assessment for a year that was never filed, which is exactly why filing it is what closes it.
A substitute for return is not your return.
When the IRS files for you it takes the reported income and stops. No cost of goods, no mileage, no depreciation, no basis on the stock the broker reported at full proceeds, no dependents, and usually married filing separate or single. We file the real return for that year, and the assessment is adjusted to it. Replacing an SFR is the single most common way the balance on these cases falls.
Pricing, on the page.
Published prices · Quoted in writing before any work startsHow it works: one annual fee, half paid at engagement and half before your return is filed. Everything past the package baseline is a published add-on at a fixed price, so nobody counts forms. Books, payroll and sales tax are the only monthly items, because they are the only monthly work. See the full grid and every add-on or get your price in a minute.
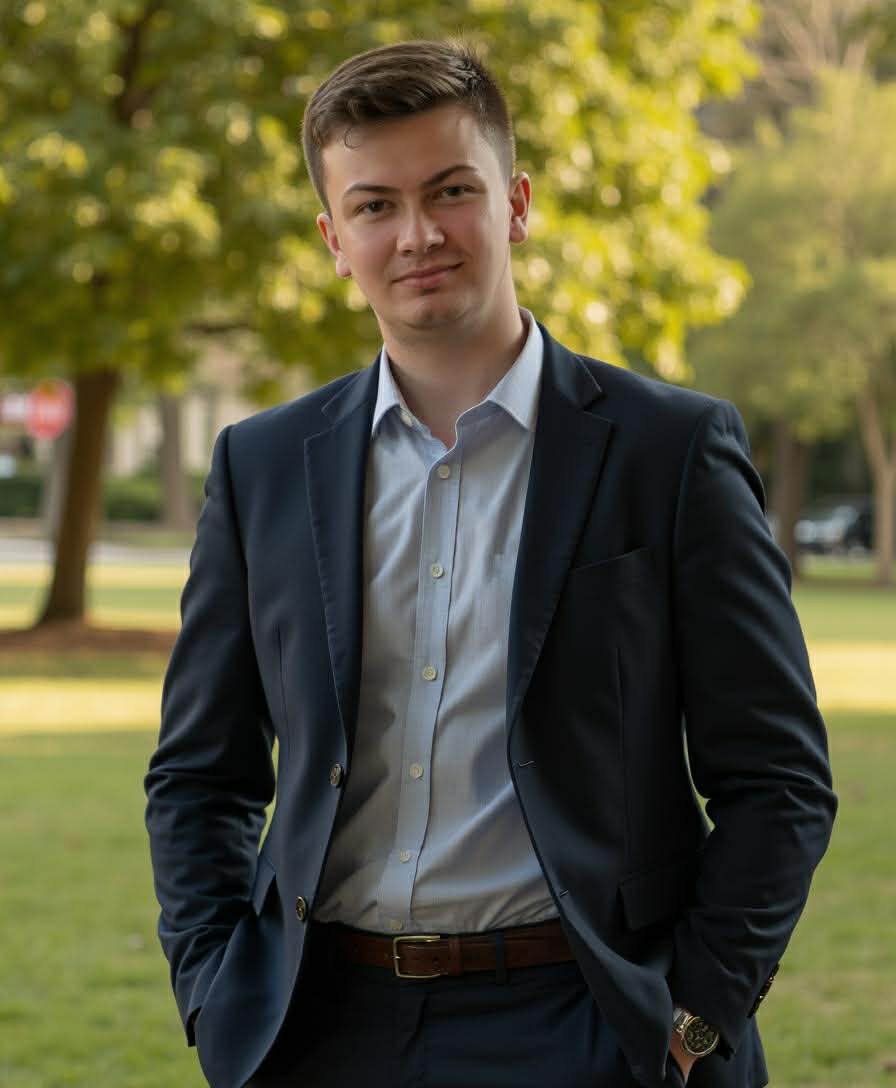
One practitioner. Every file, personally led.
Cody is an IRS Enrolled Agent with an MBA — a solo practitioner with a small support team, working out of Lakeland, Florida. He is also currently in law school.
Every client engagement is led by Cody personally. The firm stays deliberately small so the work stays deliberately careful — and so when the IRS calls, the person who picks up is the person who filed your return.
Common questions.
If yours isn't here, ask it on the intake — we read every one before the first call.
How many years do I actually have to file?
Usually the last six. That is the IRS compliance window for a non-filer, and filing those years is normally what closes the file. We check your account transcript first, because a specific year sometimes has to come in anyway — an open examination, a substitute return worth replacing, or a refund year still inside the three-year claim window.
I do not have any of my records.
Most people do not, and it is not the obstacle you think it is. The wage and income transcript rebuilds the income side almost completely. Bank and card statements, old invoices, vendor histories, mileage apps, prior-year returns and industry norms rebuild the expense side. We have filed years off far less than you are holding.
The IRS already filed a return for me. Is that final?
No. A substitute for return can be replaced by filing the actual return for that year, and the assessment is adjusted. CP59, CP515, CP516 and CP518 are the notices that say the IRS has noticed a year is missing, and Letters 1615, 3391 and 4903 are the same message in letter form: file the years, or we will. CP63 and CP88 say a refund is being held until you do. A CP2566 or Letter 2566 means the IRS has already computed a return for you and is proposing the tax, and a CP3219N is the notice of deficiency that follows it — that one starts a 90-day clock that cannot be extended, so the date on it decides everything. A year you did file but got wrong is a different fix — a 1040-X amended return, or a superseding return where the original due date has not passed yet. Amending after an IRS notice is routine and we file those too. Send whichever letter you have.
Can I still get an old refund?
Only inside three years of the original due date. Past that the refund is gone and cannot be applied to another year either. This is the one part of the job that is purely a deadline, which is why we file the oldest still-claimable year first when there is money sitting in it.
What about my passport?
When an assessed balance crosses the seriously delinquent threshold — a figure the IRS adjusts for inflation and republishes each year — the IRS certifies it to the State Department, which can deny a passport application or renewal and in some cases revoke an existing passport. Getting into an installment agreement, an accepted offer or currently not collectible status is what reverses the certification. If you travel for work, say so on the intake and we sequence the case around it.
Can the IRS take my house?
In theory, yes. A federal tax lien is real. In practice the IRS goes to wages, bank levies and refunds long before a home, and coming forward voluntarily is what stops the escalation. That is the whole point of filing first.
How long does the whole thing take?
Most non-filer cases close in 60 to 120 days from intake to current. Cases with foreign accounts, several states or a risk of criminal referral take longer, and you will know which kind yours is on the first call.
Am I going to be in trouble for this?
Almost certainly not in the way you are imagining. Criminal cases require willfulness plus real concealment, and they are rare. What we see is a divorce, an illness, a business that fell apart, one missed year that made the next one harder. The IRS treats a taxpayer who comes forward differently from one it had to find. There is no lecture here — we just file them.
Related
- IRS representationEvery representation fee published, handled by an Enrolled Agent.
- IRS payment plans and collectionsPayment plans, hardship status and levy releases, with the option you qualify for.
- IRS notice responseAny notice number answered for one flat fee of $600.
- Offer in compromiseSettling for less, only when the numbers really support it.
Tell us the years. Nobody here is going to be surprised.
You do not need your records to start. You need the years and a signature on the Form 2848.